Weekly cattle and sheep market wrap – 01 October 2026

Friday, 2 October 2026

Deadweight prices cover Great Britain (GB) for the week ending 26 September. Liveweight prices cover England and Wales (E&W) for the week ending 27 September.

Key points

  • Cattle prices continued to trend upwards with the all-prime deadweight price averaging 628p/kg. Throughput of prime cattle rose marginally on the week but remained below 2025 levels
  • New season lamb (NSL) prices rose in both the deadweight and live markets, while throughput slowed
  • Store sheep prices rose to average £120.40/head. Throughput slowed week-on-week but remained strong annually
  • Both cow and cull ewe prices ticked upwards in the latest week, while throughput of both continued to be down year-on-year
Image of staff member Molly Corbett

Molly Corbett

Analyst (Livestock)

See full bio

Cattle

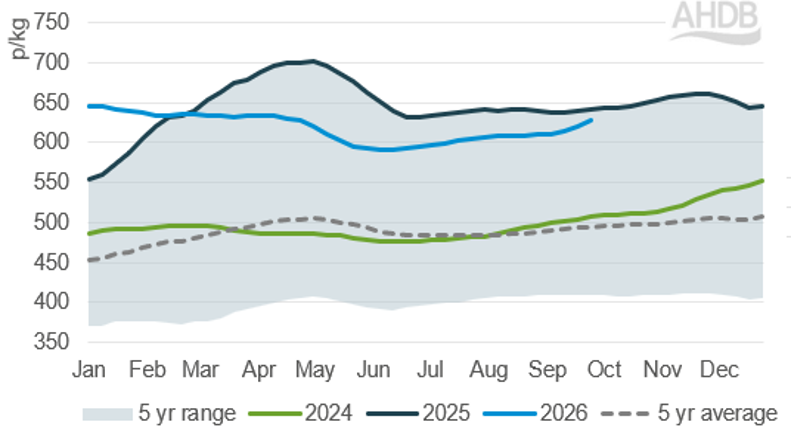
The GB deadweight all-prime cattle price gained a further 8p on the week to average 628p/kg. Tight prime cattle supplies and autumn demand continue to underpin the market, with prices now sitting just 13p below the same week in 2025.

Overall steers gained nearly 8p on the week to average 631p/kg, with overall heifers gained 7p to average 627p/kg. Young bulls posted the largest weekly gain of 11p, averaging 615p/kg.

Figure 1 shows the evolution of the GB all-prime average price over the last three years. The latest week’s price holds 134p above the five-year average. The uptick in this year’s price follows a seasonal trend ahead of typically stronger demand ahead of Christmas.

Figure 1: GB deadweight all-prime cattle price, p/kg, 2024-2026 compared with the five-year average and range

Source: AHDB

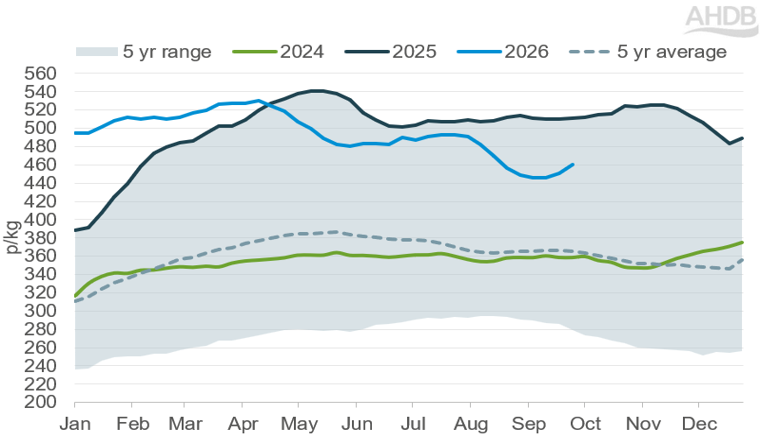
The GB deadweight cow price ticked up by 10p to average 460p/kg for the latest week. Figure 2 shows the cow price averaging 51p lower year-on-year but still up 95p on the five-year average. Values have returned to an upward trend, having fallen sharply through August.

Figure 2: GB overall average deadweight cow price chart, p/kg 2024-2026 with a 5-year average and range

Source: AHDB

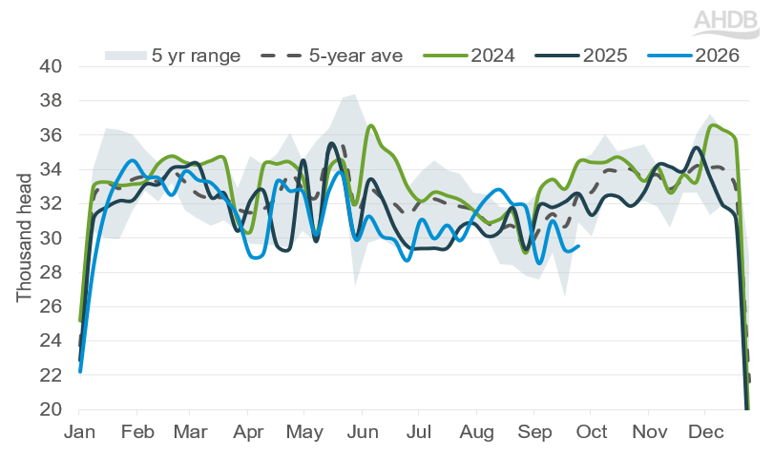
GB estimated prime cattle slaughter rose marginally on the week to 29,500 head but was 3,000 head below year-earlier levels. Continued tight availability of finished cattle is helping support prices as processors compete for supply.

Figure 3 shows how prime cattle throughput has been below the five-year average for much of the year.  

Figure 3: GB estimated weekly prime cattle slaughter, thousand head 2024-2026 with a 5-year average and range

Source: AHDB, Defra. Figures may be subject to revision.

At a UK level, Defra figures show that prime cattle kill for the year-to-date (Jan-Aug) has been 1% lower year-on-year, with tightness particularly evident through the first six months. Kill through July and August rose by 1% and 3% respectively. However, with carcase weights on average 9.5kg/head heavier, UK beef production has grown by 1% on the year.

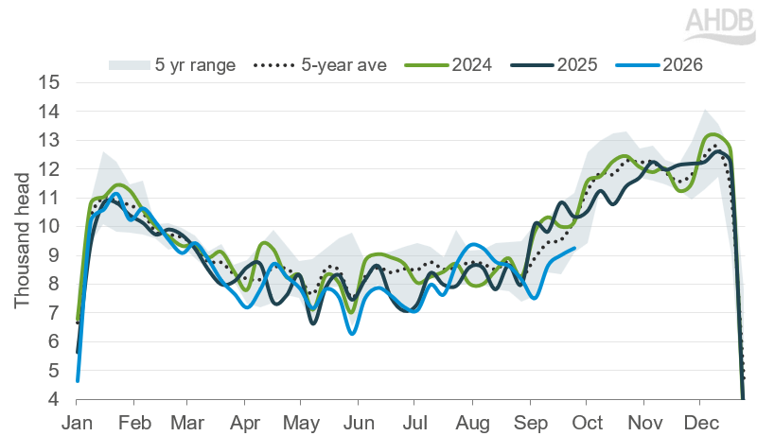
Estimated weekly GB cow slaughter rose week-on-week by 200 head to total 9,200 head. Figure 4 shows estimated cow slaughter over the past three years. Throughput in 2026 has generally trended below the five-year average and has often sat at the lower end of the historical range.

Figure 4: Estimated weekly GB cow slaughter, thousand head 2024-2026 with a 5-year average and range

Source: AHDB, Defra. Figures may be subject to revision.

Sheep

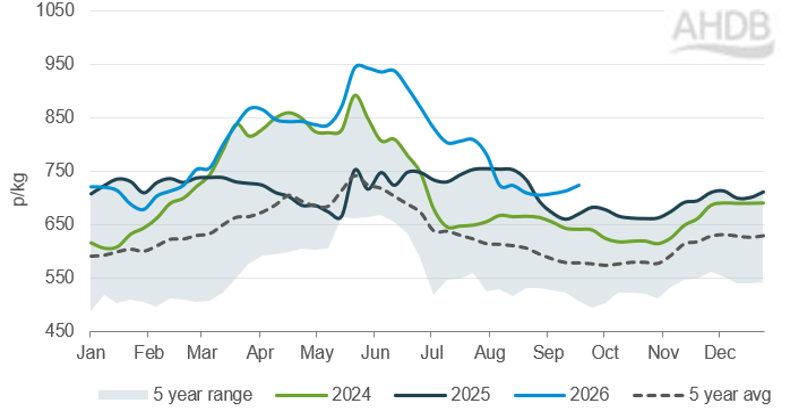
The GB deadweight overall new season lamb (NSL) SQQ ticked up by 8p in the latest week to average 732p/kg, up 49p year-on-year.

Figure 5 shows the relative strength in GB deadweight lamb prices currently. The NSL price in 2026 has been ahead of last year’s price for much of the season, despite a drop from the end of July into August. The price has lifted again, following a seasonal pattern ahead of Christmas procurement.

Figure 5: GB deadweight lamb SQQ (overall), p/kg from 2024-2026 with a 5-year average and range

Source: AHDB

Note: The old season lamb price is reported until the third Monday in May, with NSLs then reported for the remainder of the year.

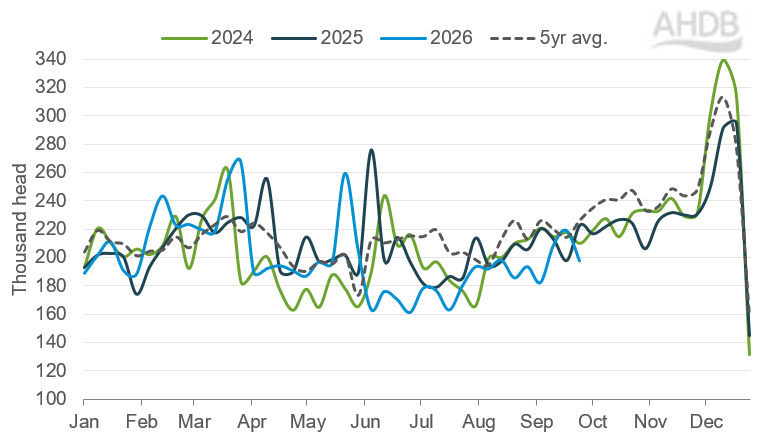
Figure 6 shows the evolution of estimated GB clean sheep slaughter. Greater hogget slaughter at the beginning of 2026 kept supply up, but more recently, supply has remained below 2025 levels. Clean sheep slaughter fell by 11% in the most recent week to 197,700 head.

Figure 6: Estimated weekly GB lamb slaughter numbers, thousand head 2024-2026 with a 5-year average

Source: AHDB, Defra (Figures may be subject to revision)

In live markets, the NSL SQQ price rose 2p week-on-week to average 341p/kg, up 34p on the year. Cull ewe prices rose by £2.10 to average £136.10/head, up £27.60 on the year.

Finished NSL throughput dropped 3% to 43,200 head, 12% lower year-on-year. Cull ewe throughput fell by 7% week-on-week to 32,000 head, down 12% versus the same week a year ago.

Meanwhile, the store trade has been strong. Store lambs in E&W averaged £120.40/head, up 22% on the year. Store lamb throughputs fell slightly week-on-week to 57,100 head, still 10% higher than the same week a year ago.

Year to date throughput of NSL store lambs has been up 9% year-on-year.

Tighter forage conditions, strong prices and disease pressure would underpin increased store lamb marketings.

© Livestock Auctioneers Association Limited 2026. All rights reserved.


Sign up for regular updates

You can subscribe to receive beef and lamb market news straight to your inbox. Simply fill in your contact details on our online form.

Visit the AHDB Preference Centre to keep in touch

While AHDB seeks to ensure that the information contained on this webpage is accurate at the time of publication, no warranty is given in respect of the information and data provided. You are responsible for how you use the information. To the maximum extent permitted by law, AHDB accepts no liability for loss, damage or injury howsoever caused or suffered (including that caused by negligence) directly or indirectly in relation to the information or data provided in this publication.

All intellectual property rights in the information and data on this webpage belong to or are licensed by AHDB. You are authorised to use such information for your internal business purposes only and you must not provide this information to any other third parties, including further publication of the information, or for commercial gain in any way whatsoever without the prior written permission of AHDB for each third party disclosure, publication or commercial arrangement. For more information, please see our Terms of Use and Privacy Notice or contact the Director of Corporate Affairs at info@ahdb.org.uk  © Agriculture and Horticulture Development Board. All rights reserved. 

Topics:

Sectors:

Tags:

×