Beef market outlook

October 2026

Key points

  • UK beef production is forecast at 904,000 tonnes for 2026, up by 1.0% on 2025 levels, with increased carcase weights counteracting lower throughputs
  • Looking ahead to 2027, beef production is forecast to fall a further 0.8% on the 2026 forecast, with continued contraction in the cattle herd and carcase weights remaining stronger
  • Import volumes for the full year of 2026 are forecast to grow 3% on 2025 levels, with increased volumes weighted to the second half of the year. Exports are forecasts up 3% for the full year, with a strong annual uplift in Q1 counteracting small year-on-year declines expected in the remaining quarters
  • Domestic beef consumption volumes in 2026 are expected to be limited as high prices at shelf edge continue to weigh consumer purchases
  • Historically tight supplies are likely to continue to support cattle prices, however subdued consumer demand and a changing imports mix have the potential to weigh on any significant price growth
Image of staff member Becky Smith

Becky Smith

Senior Analyst (Livestock)

See full bio

Overview

The 2026 market has been characterised by lower domestic cattle numbers, challenged consumer demand and evolving global trade.

We have seen a relatively steady pricing landscape, compared to the volatility of 2025, but uncertainty around domestic policy, extreme weather and continued profitability challenges mean that producer confidence remains fragile.

For the remainder of the year, we anticipate that tight cattle supplies will continue to underpin prices at a historically high level. While consumers continue to spend more on beef, high retail prices restrict volumes purchased, particularly in more premium cuts, which weighs on price growth at the farmgate.

Developments in trade and market access for key players on the global beef market will influence product flows and the effect of these movements on the domestic market remains an important watch point.

Looking ahead to future cattle supplies, the contraction in the beef breeding herd appears to be slowing. Calf registrations for beef production saw a slight uplift in Q1, which is likely a reaction to the high prices of spring 2025. Registrations have, however, have eased back again in Q2, indicating again the fragility of producer confidence and suggesting that supply contraction is likely to continue over the coming years.

Supply

Prime cattle slaughter

UK prime cattle slaughter for the first eight months of this year has totalled 1.32 million head, 1.0% lower than the same period of 2025. Slaughter was lower year-on-year through H1 but in July and August we saw numbers higher than the same months of 2025.

Looking at the remainder of 2026, we expect that prime cattle slaughter will trend slightly higher than last year’s Q3 and Q4, as we annualise against extremely tight cattle supplies.

For the full year of 2026, we forecast prime cattle slaughter at 1.99 million head, back 0.8% on 2025, and reflecting continued contraction in the national beef herd.

Looking ahead into 2027, we anticipate this shortening in cattle throughput to continue, with total prime slaughter sitting at 1.98 million head, a further 0.9% decline on the 2026 forecast.

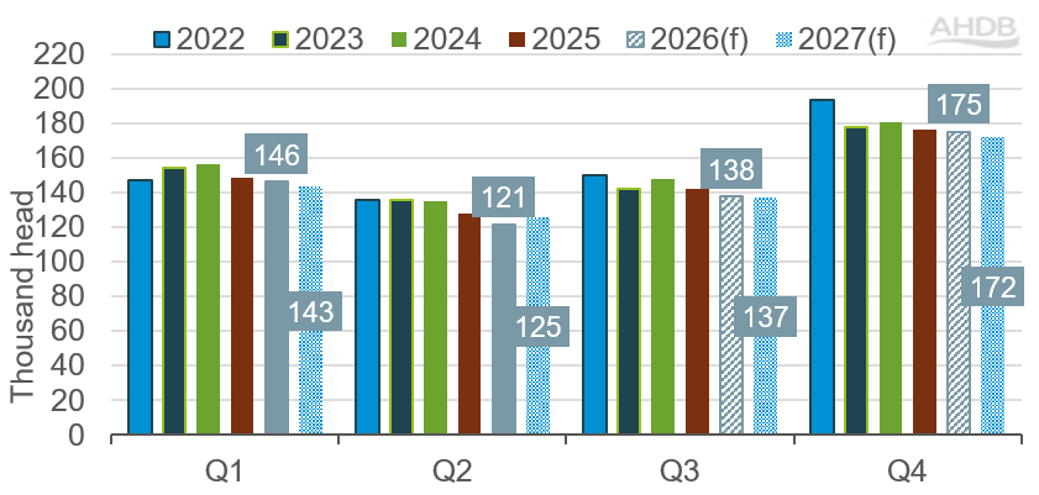
Figure 1. Actual and forecast (f) quarterly UK prime cattle slaughter, 2022–2027

Source: Defra, AHDB. Forecasts in hashed bars

Figure 1 shows actual figures from Defra with AHDB forecasts for 2026 in the hashed bars. UK prime cattle slaughter is forecast to fall year-on-year in Q1 and Q2 of 2026 with a slight uplift in Q3 and some growth in Q4.

Cow slaughter

For 2026 to date (Jan-Aug) cow slaughter has totalled 355,000 head, back by 2.2% versus 2025. This is representative of both the continued contraction of the suckler cow herd, and increased dairy cow kill in the latter part of 2025 following falls in milk prices, both of which have limited numbers available for slaughter this year.

We forecast that for the full year of 2026, cow slaughter will total 580,000 head, a 2.4% decline year-on-year. Declines will be felt across Q3 and Q4, with an uplift in Q2 driven by forage shortages, likely increasing offloading.

In 2027, cow kill is forecast to fall a further 0.5% year on year, to 577,000 head.

Figure 2. Actual and forecast quarterly UK cow slaughter, 2022–2027

Source: Defra, AHDB forecasts in hashed bars

Figure 2 shows actual figures from Defra, with AHDB forecasts for 2026 in the hashed bars. UK cow slaughter is forecast to fall year-on-year in 2026.

Beef production

In the first eight months of 2026, beef production has totalled 589,000 tonnes, up by 1.0% on the same period of last year. Whilst cattle numbers have been limited, higher weights have boosted production with prime cattle carcase weights up by 10kg on average so far this year.

For the full year of 2026, beef production is forecast to total 904,000 tonnes. This is a 1.0% growth on 2025 levels, driven by higher carcase weights throughout the year.

Beef production in 2027 is forecast at 896,000 tonnes, a fall of 0.8% on the 2026 forecast. This takes into account continued contraction in cattle numbers, combined with sustained high carcase weights from 2026.

Figure 3. Actual and forecast (f) UK beef production 2022-2027, with year-on-year change

Source: AHDB

Figure 3 shows actual figures for 2022 to 2025 from Defra, with the AHDB forecast for 2026 and 2027 in the hashed bar. UK beef production is forecast to fall year on year in 2026 and 2027.

Impact of bluetongue virus

This outlook does not account for the risk of a disease outbreak or severe weather conditions in the year ahead, both of which could lead to above-average mortality or production losses in the current cattle herd and effects on fertility which would influence future supplies.

At the time of writing, on 14 October, there were 3,370 farms (premises) with confirmed cases of bluetongue (BTV-3) in the UK in the 2026-27 season. There are high-level concerns across the industry about the degree to which bluetongue could impact individual farms and domestic cattle and sheep production. The latest information on the outbreak can be found on the Government website.

Assessing how the bluetongue outbreak will shape our outlook is challenging as much remains unknown about levels of infection and mortality from the disease and uptake of vaccination. To address this challenge, we have developed a likely bluetongue scenario. This was developed using farmer survey evidence combined with anecdotal evidence from vets, farmers and farming organisations.

This is based on the geographic spread of Bluetongue being concentrated in the South West, West Midlands, East Midlands, North West, Yorkshire (South and West) and Wales. The scenario is based on 50% of cattle within 25% of the herds in these areas becoming infected (12.5% of all animals in these regions becoming infected, spread evenly across age groups). Mortality rates are assumed to be 1% across all cattle types with fertility dropping by 25% for infected cows.

We have modelled a range of scenarios given the uncertainty on impacts and have found that at a national scale these do not materially change the production outlook in comparison to the 'most likely' scenario. It is however possible that the true impact of bluetongue could be more or less severe than forecast.  

Given that mortality in cattle is significantly less severe than in sheep, the impact of this bluetongue scenario on production for 2026 and 2027 is minimal. The most significant effect is on the fertility of cows and the viability of calves born from cows infected during pregnancy. Therefore, the largest impact in this likely scenario is a reduction in the number of calves born in 2027, with modelling indicating a potential reduction of 14,000 head (3.1%) of calves.

Taking into account the cattle production cycle, the impact of these losses are not felt materially in the production forecast until 2029. Here, the losses account for a further 0.2% fall (around 8,000 head) in prime cattle kill, beyond the forecast.

A significant uncertainty in this scenario is the scale of uptake of bluetongue vaccination. Data on vaccines bought or ordered is not published by government. We have assumed that vaccine uptake has been modest in 2026 and will only become widespread in the 2027/28 season. A quicker uptake of vaccination would shift cattle production closer to our baseline forecast.

Trade

Imports

In the first seven months of 2026 (Jan-Jul) total beef imports (fresh, frozen, processed and offal) totalled 177,800 tonnes (product weight). This was 2.4% higher than the same period of 2025, with growth in imports from Brazil, New Zealand and Australia offsetting declining volumes from Ireland and Poland.

The value of these imports totalled £1.29 billion, up 10.6% year-on-year.

Figure 4. UK total* beef import volume by supplier, YTD (Jan-Jul)

Source: UK HMRC via Trade Data Monitor

* Total beef imports include fresh, frozen, processed and offal

Figure 4 shows trends in UK beef imports from key suppliers from 2022 to 2026. Imports have remained relatively level over the period, with growth from 2025 to 2026.

Looking to the remainder of 2026, we anticipate that beef imports will remain higher versus last year.

A wider price differential between GB and Irish farmgate values, coupled with forecasts for a more normal seasonal supply pattern in Irish kills for the second half of this year may encourage more Irish beef into the UK market.

Furthermore, we may anticipate greater volumes of beef shipped to the UK from Brazil, as access to the EU has been withdrawn for the remainder of 2026. Imports from Australia and New Zealand remain key watchpoints, particularly as access to the UK market increases under FTA agreements.

We forecast that for the full-year of 2026, beef import volumes will be 3% higher versus 2025

Exports

In the year-to-date (Jan-Jul) UK beef exports (fresh, frozen offal and processed) totalled 82,000 tonnes, representing growth of 4% on last year’s levels. This was valued at £522 million.

The EU remains the key market, taking 80% of all products. Significant growth was seen in exports to Ireland, likely reflecting the closer prices at the start of the year.

Figure 5. UK total* beef exports by destination, YTD (Jan-Jul)

Source: UK HMRC via Trade Data Monitor

* Total beef imports include fresh, frozen, processed and offal

Figure 5 shows trends in UK beef exports from key suppliers from 2022 to 2026. Beef exports have fluctuated over the period and show growth from 2025 to 2026.

For the full year of 2026 UK beef exports are forecast to grow by 3% year-on-year. This accounts for a very strong export trade in Q1 (+15% YoY), and then smaller annual falls in the remaining quarters of this year.

Exports are likely to be somewhat limited by domestic production, with less product available to ship. The European Commission is forecasting a notable increase in import demand, which may offer opportunity. Demand for beef remains strong globally but the higher price point of British product underscores the importance of targeting premium markets.

Looking ahead to 2027, global beef supply is expected to remain tight as key suppliers in Australia, Brazil and the US look to rebuild their herds. This, combined with a lower domestic demand forecast may limit import volumes to the UK.

Exports in 2027 are likely to continue to be limited by domestic production, although consistent demand from the EU and the growth in new export destinations could support both volumes and value.

Cattle price outlook

Cattle availability remains tight for the remainder of 2026, with lower numbers likely to continue to support prices at an elevated level, compared to the five-year average. In the first half of 2026 we saw increased cattle weights support production volumes which alleviated this tightness to some extent, which is likely to continue into the second half of the year. However, we still anticipate the structural tightness to underpin markets.

The global cattle market and the impact of changing trade patterns remain key watchpoints. As outlined above, changes to global trade flows, such as China’s safeguards measures, the EU’s ban on Brazilian beef and changes to US tariffs have the potential to increase or decrease the amount of beef on the global market, and in turn the volume and mix of product coming into the UK. Significant changes in the volume of imports or the product mix have the potential to weigh on domestic farmgate prices.

Consumption

In the past 52 weeks, higher average prices have seen retail beef spend grow +7.1%1 and out-of-home (OOH) spend grow +1.2%2 year-on-year. These higher prices have led to a retail volume decline of -4.6%1 and an OOH volume decline of -2.9%3.

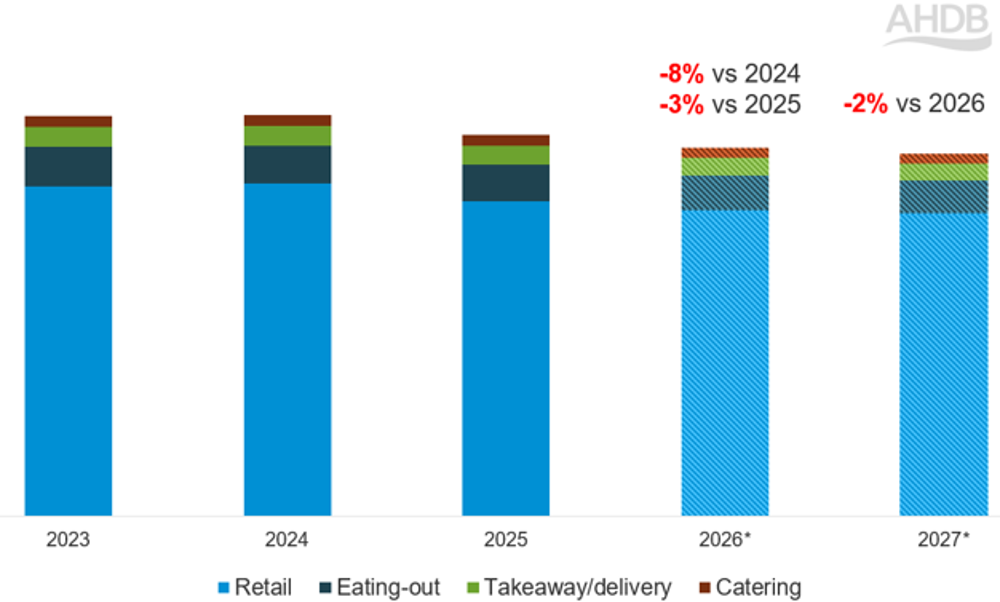
Our revised forecast for total UK beef volumes in 2026 is -3% versus 2025 (a -8% decline versus 2024).

For 2027, we expect consumer confidence to remain muted. Rising food inflation and energy costs will add pressure to household incomes, as detailed in our economic outlook. Consumers are likely to make careful spending decisions, focusing on getting the best value for money.

We forecast total beef volumes in 2027 to be -2% versus 2026.

For further information and latest trends for beef, visit our GB household beef purchases dashboard and our foodservice dashboard.

Figure 6. Actual and forecast volumes of beef sold in the UK

Source: AHDB volume estimates for UK based on Worldpanel by Numerator UK retail and OOH data. *2026 and *2027 figures are AHDB estimates

Figure 6 shows volumes in 000kg for beef sales in UK split by retail, eating-out, takeaway/delivery and catering. Actual volumes are shown for 2023 through to 2025. AHDB estimated volumes are shown for 2026 and 2027. Over the 5-year period, retail is consistently the largest component. AHDB estimates volumes for 2026 will decline 3% versus 2025 and decline 8% versus 2024. AHDB estimates volumes for 2027 will decline 2% versus 2026.

Retail demand

Volume sales for beef mince will remain muted as consumers turn to more cost-effective solutions for family friendly meals. Boredom from too many chicken meals may bring beef mince back into consideration. Consumers may turn to comfort food such as cottage pies and lasagnes.

Consumers will shop around for the best deals. Promotions on steaks and roasting joints will help drive volumes for key celebrations.

Another hot dry summer is forecast for 2027 which will help sales of burgers for BBQ cooking.

Scratch cooking main meal occasions have increased by 4% in the past year, with these meals being viewed as healthier and cheaper than other preparation methods4.This trend will favour simple, easy and quick meals with beef such as spaghetti bolognese.

In the UK, 8% of individuals use GLP-1 medication, a 3.1% increase over the past nine months5. Beef, as a good source of protein, may benefit from the growth in GLP-1 users looking for high-quality protein in small portions.

Out-of-home demand

Consumers will reserve dining-in for special occasions focussing on steaks and roasting joints. Fast food restaurants are likely to focus on smaller, cheaper beef burgers for cost conscious consumers. Larger, more indulgent burgers will appeal to consumers looking for a premium treat.

Takeaways are forecasted to slowly decline following a post-covid boom. There may be a potential uplift in volumes through delivery apps for the Woman’s World Cup in the summer months.

How might the beef outlook be improved?

The beef demand outlook might be further boosted, if the industry:

  • Ensure there is a wide range of pack sizes and quality options to keep British beef accessible for all consumers irrespective of budget
  • Inspire with beef recipes that are cost effective, family friendly, filling and reduce waste with batch cooking
  • Promote beef in-store around key events and festivals to encourage shoppers to choose beef options
  • Capture big-night-in occasions through inspirational premium offerings such as restaurant quality dine-in meal deals
  • Help shoppers re-engage with beef in the meat aisle, with well-signposted ranges, strong quality cues and British assurance
  • Engage with consumers regularly to maintain and build trust. Share the work that farmers are doing in the UK around animal welfare, environmental stewardship and their high levels of expertise to provide quality food products

We have a range of marketing activities planned for the year, including the Let’s Eat Balanced campaign. Please visit our marketing pages for more information.

For more insight around consumer demand, visit our retail and consumer pages.

Sources:

1Worldpanel by Numerator UK, 52 w/e 6 September 2026

2Worldpanel by Numerator UK OOH, 52 w/e 6 September 2026

3AHDB estimates based on Worldpanel by Numerator UK OOH, 52 w/e 6 September 2026

4Worldpanel by Numerator UK, Usage panel, 52 w/e 14th of June 2026

5IGD, May 2026

Image of staff member Emma Wantling

Emma Wantling

Retail and Consumer Insight Manager

See full bio

While AHDB seeks to ensure that the information contained on this webpage is accurate at the time of publication, no warranty is given in respect of the information and data provided. You are responsible for how you use the information. To the maximum extent permitted by law, AHDB accepts no liability for loss, damage or injury howsoever caused or suffered (including that caused by negligence) directly or indirectly in relation to the information or data provided in this publication.

All intellectual property rights in the information and data on this webpage belong to or are licensed by AHDB. You are authorised to use such information for your internal business purposes only and you must not provide this information to any other third parties, including further publication of the information, or for commercial gain in any way whatsoever without the prior written permission of AHDB for each third party disclosure, publication or commercial arrangement. For more information, please see our Terms of Use and Privacy Notice or contact the Director of Corporate Affairs at info@ahdb.org.uk  © Agriculture and Horticulture Development Board. All rights reserved. 

×