Arable Market Report – 09 November 2026

Monday, 9 November 2026

This week's view of grain and oilseed markets, including a summary of both UK and global activity.

Grains

UK feed wheat futures May-2027

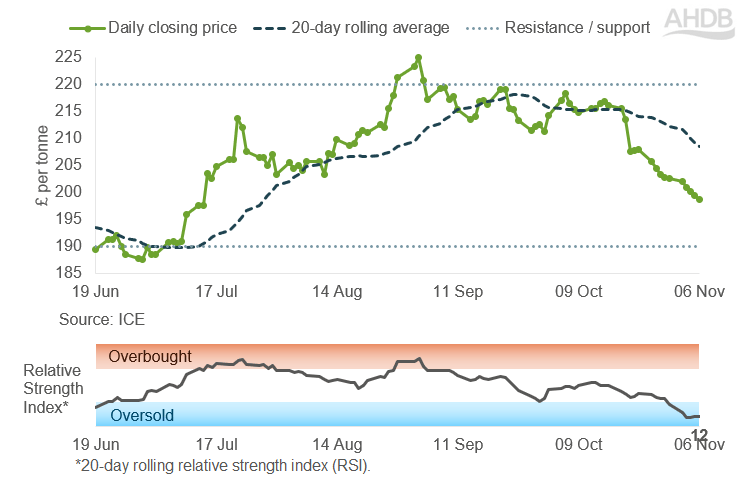
Figure 1. UK feed wheat futures prices, May-2027 contract, in £/tonne

UK feed wheat graph 09 11 2026

UK feed wheat followed Paris milling wheat futures lower last week, with May-2027UK feed wheat falling 1.9%. The May-2027 contract closed at £198.75/t, losing £3.75/t week-on-week.

The May-2027 contract prices are shown by the solid line with markers in Figure 1.

Prices have continued below the 20-day moving average and momentum indicators have weakened again. This suggests near-term downside pressure, unless new information comes forward.

The market has now entered oversold territory.  The Relative Strength Index (RSI) was at 12 on Friday, reflecting the limited momentum.

Find out more about the graphs in this report and how to use them

Market drivers

Global grain markets fell across the week, with Paris milling wheat futures (May-27) down 2.5%. Chicago maize and wheat (May-27) were down 1.2% and 2.4%, respectively.  

Markets were pressured by improving global supply prospects, US harvest progress, falling crude oil prices, and hopes of Russia–Ukraine peace talks. These outweighed support from continued Black Sea export disruption.

Geopolitical tensions in the Black Sea remain a key watchpoint. Strikes on merchant shipping are continuing to disrupt Russian and Ukrainian seaborne grain exports. The upcoming peace talks on the 10-11 November offer some hope of a resumption of Black Sea shipments, but its outcome remains a key watchpoint.

With the US export demand falling behind last year’s pace, a new US wheat and sorghum sales agreement with Chinese buyers gave some support. That said, uncertainty over future Chinese demand remains.

With the US maize harvest reported 74% complete by 2 November, the weather risk premium for the harvest has almost fully unwound. With favourable weather last week, the crop progress report coming out tonight will likely show the harvest nearing completion. Dry weather is also forecast for the coming seven days in key maize producing states.

Traders are adjusting positions ahead of the USDA's World Supply and Demand Estimates report on Tuesday 10 November. After errors in its September maize data, the USDA will use an artificial intelligence tool to check this report, which may give the market more confidence in the figures. Analysts expect a slight cut to the US maize production estimate, but the expected crop would still be the second-largest on record.

However, private estimates show there is still uncertainty over the final crop size. StoneX has raised its US maize yield and production forecasts. Either way, ample supply is likely to keep limiting any upside in the near term.

Table 1. Global grain futures prices

Futures marketContract monthPrice per tonneChange on week
UK feed wheat May-2027 £198.75 −£3.75
Paris milling wheat May-2027 €222.75 −€5.75
Chicago wheat May-2027 $223.56 −$5.60
Chicago maize May-2027 $182.48 −$2.17

n/a = not available

n/c = no comparison available

UK delivered cereal prices

To ensure our published prices remain robust and representative of the market, we are not publishing any UK delivered cereal prices as at Thursday 5 November 2026. This is because we received insufficient quotes to calculate a price fully reflective of the market. 

Rapeseed

Paris rapeseed futures in £/t, May-2027

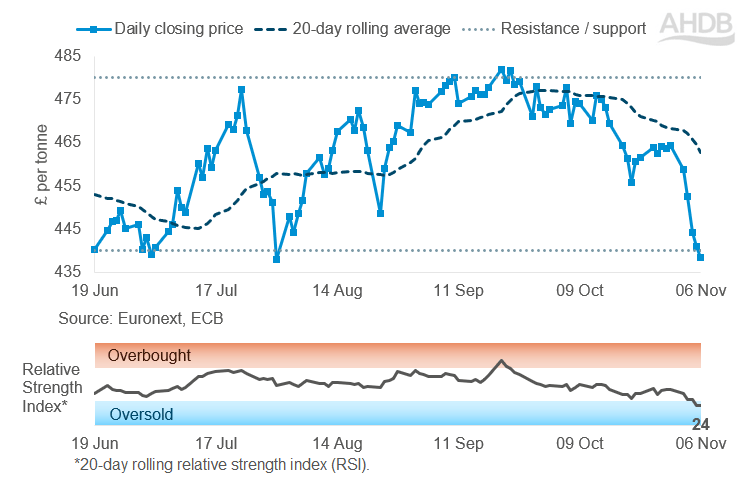
Figure 2. Paris rapeseed futures prices, May-2027 contract, in £/tonne

Paris OSR graph 09 11 2026

Paris rapeseed futures fell sharply over the week, dropping below key technical support levels and ending under £440/t.  In £ per tonne, the May-2027 contract lost 6%.

Continued pressure from weakness across the wider oilseed complex and expectations of ample global supplies weighed on prices.

Since the start of October, sterling has strengthened against the euro. This has added further pressure to UK rapeseed values by lowering the sterling-equivalent value of Paris rapeseed futures.

Find out more about the graphs in this report and how to use them

Market drivers

Oilseed markets came under pressure over the past week. They were driven primarily by ongoing US soyabean harvest progress, weakness in crude oil markets and Brazilian soyabean planting progress.

Chicago soyabean futures for May-2027 fell 3.6%. May-2027 Paris rapeseed futures were down 5.6%, and Winnipeg canola futures were down 4.0%.

Soyabeans hit a 12-week low last week as US harvest pressure continues to weigh on the oilseed complex. 88% of the US soyabean harvest was complete by 1 November, ahead of the five-year average. Further updates are expected this evening (21:00 GMT) in the USDA crop progress report. With this US crop finishing up market attention will soon switch to South American supplies.

At the end of last week, it was reported that Brazil's 2026 soybean planting reached 65% of the intended area by 6 November. This was ahead of the 58% planted at the same point last year, according to Patria Agronegocios. Faster planting progress supports expectations for another large Brazilian soybean crop but will also aid the second maize crop plantings at the start of 2027.

The USDA's Beijing attaché forecasts China's 2026/27 soybean imports at 110 Mt, 5 Mt below the USDA's official estimate of 115 Mt. The lower forecast reflects differing expectations for Chinese demand, although China is still expected to remain the world's largest soybean importer.

Nearby Brent crude oil weakened over the week, with the contract closing the week at $98.32/barrel. This is down $15.11/barrel Friday to Friday.

Concerns over supply disruptions eased following progress in US-Iran discussions. Meanwhile, expectations of ample global oil supplies and ongoing OPEC+ policy uncertainty added further downward pressure to prices.

The USDA's November WASDE report, due to be released on Tuesday, remains a key watchpoint for oilseed markets. Trader estimates suggest US soybean production could be revised higher on improved yields, further boosting global oilseed supplies as a record US crop comes to market.

Table 2. Global oilseed and oil futures prices

Futures marketContract monthPrice per tonneChange on week
Paris rapeseed May-2027 €525.75 −€31.25
Chicago soyabeans May-2027 $443.91 −$16.62
Chicago soyabean oil May-2027 $1,397.72 −$79.59
Brent crude oil* nearby $98.32 −$15.11

*Brent crude oil price per barrel
n/a = not available
n/c = no comparison available

UK delivered rapeseed prices

The delivered price for rapeseed into Erith in November was £443.50/t in Friday’s survey, down £22.00/t from the previous week. The delivered price for Liverpool in November was also £443.50/t, down £22.00/t on the week.

The delivered price into East Anglia in November was £442.50/t, down £21.50/t week-on-week.

The market pressure also fed into new crop values with Harvest 2027 delivered prices at £428.00/t for both Erith and Liverpool, down £20.50/t week-on-week. For East Anglia Harvest 2027 was quoted at £427.00/t, with no comparison available on the week.

Table 3. UK delivered rapeseed prices

Delivery specificationDelivery monthPrice per tonneChange on week
Erith May-2027 £452.50 −£21.50
Liverpool May-2027 £452.50 −£21.50
East Anglia May-2027 £451.50 −£21.00

n/a = not available

n/c = no comparison available

Extra information

AHDB's Early Bird Survey, due for release on Friday 13 November, will provide the first indication of UK cereal and oilseed planting intentions for harvest 2027. The results will offer an early insight into potential crop area changes and implications for domestic grain and oilseed supply in 2027/28.

The 2026 AHDB Cereal Quality Survey results are now available and show exceptionally high milling wheat quality, but mixed quality for barley, from this year's harvest.

HMRC is due to release data on UK imports and exports in September on Thursday, 12 November.

Cereals usage data

AHDB published data on GB animal feed production and UK human and industrial cereal usage in September last week.

Usage of barley by UK brewers’, maltsters’ and distillers’ from July – September fell 13% year-on-year, though the rate of decline slowed over the period.

The total wheat milled from July – September also declined 5% year-on-year. However, 1% more home-grown wheat was used in the period than 2025, while imported wheat usage fell by 21%.

The fall at the headline level is likely influenced by lower demand from the bioethanol sector as Vivergo closed in August 2025.

In contrast, UK oat millers used 7% more oats in July – September than the same period in 2025.

Northern Ireland

Table 4. Delivered prices into Belfast*

Delivery specification**Delivery monthPrice per tonneChange on week
Feed barley  - spot Spot n/a n/a
Feed barley  - forward Feb-2027 £209.00 n/c
Feed wheat  - spot Spot n/a n/a
Feed wheat  - forward Feb-2027 n/a n/a

*Prices provided for indicative purposes
**Basis is imported/home-grown
n/c = no comparison
n/a = not available.


Sign up to receive the latest information from AHDB

While AHDB seeks to ensure that the information contained on this webpage is accurate at the time of publication, no warranty is given in respect of the information and data provided. You are responsible for how you use the information. To the maximum extent permitted by law, AHDB accepts no liability for loss, damage or injury howsoever caused or suffered (including that caused by negligence) directly or indirectly in relation to the information or data provided in this publication.

All intellectual property rights in the information and data on this webpage belong to or are licensed by AHDB. You are authorised to use such information for your internal business purposes only and you must not provide this information to any other third parties, including further publication of the information, or for commercial gain in any way whatsoever without the prior written permission of AHDB for each third party disclosure, publication or commercial arrangement. For more information, please see our Terms of Use and Privacy Notice or contact the Director of Corporate Affairs at info@ahdb.org.uk  © Agriculture and Horticulture Development Board. All rights reserved. 

×