Arable Market Report – 16 November 2026

Monday, 16 November 2026

This week's view of grain and oilseed markets, including a summary of both UK and global activity.

Grains

UK feed wheat futures, May-2027

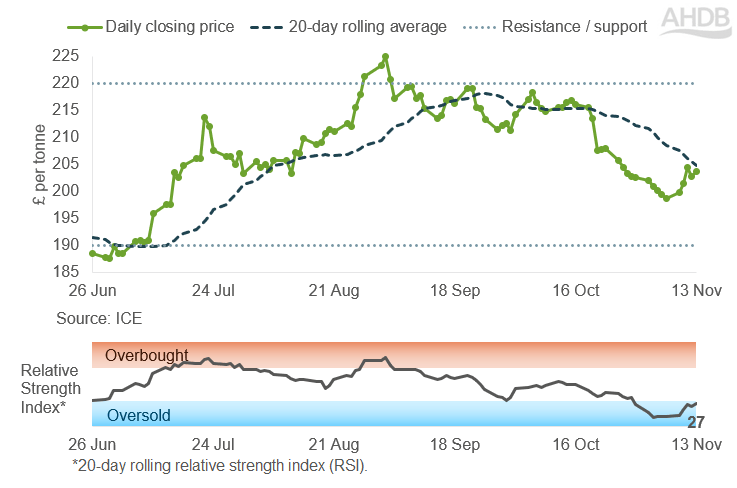
Figure 1. UK feed wheat futures prices, May-2027 contract, in £/tonne

May-2027 UK feed wheat futures ended last week at £203.75/t, gaining £5.00/t or 2.5% over the week.

The contract also moved back above the key psychological level of £200/t. However, it remained just below the 20-day rolling average on Friday, which could act as a resistance line moving forward.

A resistance line is a price level that prices can find it harder to move above.

In Figure 1, the solid line with markers shows the May-2027 prices, while the dashed line shows the 20-day rolling average price.

Due to the price rises, the Relative Strength Index (RSI) moved up from 12 on 6 November to 27 on 13 November.

While still in the overbought zone, this is the highest RSI for over two weeks and could start to offer some support at the current levels.

Find out more about the graphs in this report and how to use them

Market drivers

After heavy falls in the previous weeks, European grain markets lifted a little last week. The euro weakened against the US dollar, helping the competitiveness of EU exports, while Black Sea exports remain below normal.

The potential for Black Sea exports to improve had weighed heavily on prices ahead of negotiations between Ukraine, Russia and the US resuming last week. While the countries report some progress, there are also still major differences (LSEG).

There was also a drone attack on one of Russia’s Baltic ports midweek.

Meanwhile, the USDA cut its estimates of the US maize crop and end-of-season stocks by more than the market had expected. This reduction supported global grain prices.

However, increases to global wheat production and maize, due to strong supplies from the Southern Hemisphere, limited the price gains.

The USDA increased its estimate for the 2026/27 Argentinian and Australian wheat crops by 1.5 Mt each. The agency also added 2.0 Mt each to the Argentinian and Brazilian maize crops.

May-2027 Paris wheat futures gained 2.6% last week. However, nearer delivery months gained more, reflecting tighter near-term supplies, with the Dec-2026 contract up 3.6%.

The gains in US markets Friday-Friday were more muted due to a stronger US dollar. The Chicago futures May-2027 contract for wheat gained 0.6%, with maize up 0.1%.

Meanwhile, more information is emerging on winter crops for harvest 2027.

FranceAgriMer reported 94% of French winter barley in good or very good condition by 9 November, slightly below last year’s 98%, with planting almost complete.

However, like in southern areas of the UK, above-average rainfall will be needed this winter to support French groundwater levels.

Currency and Black Sea exports are likely to remain key factors this week.

Table 1. Global grain futures prices

Futures marketContract monthPrice per tonneChange on week
UK feed wheat May-2027 £203.75 +£5
Paris milling wheat May-2027 €228.50 +€5.75
Chicago wheat May-2027 $224.94 +$1.38
Chicago maize May-2027 $182.68 +$0.20

UK delivered cereal prices

The delivered price for feed wheat in East Anglia in November was £199.50/t last week, with no week-on-week comparison available.

Meanwhile, the price for the same delivery (November) in North Humberside was £208.50/t.

For bread wheat in December, the delivered prices reported were £214.50/t into London/Essex and £223.00/t in Yorkshire.

Table 2. UK delivered wheat prices

Delivery specificationDelivery monthPrice per tonneChange on week
London/Essex bread wheat Dec-2026 £214.50 n/c
E. Anglia feed wheat Nov-2026 £199.50 n/c
Yorkshire feed wheat Nov-2026 £208.50 n/c
E. Anglia feed barley Nov-2026 n/a n/a

n/a = not available
n/c = no comparison available

Rapeseed

Paris rapeseed futures in £/t, May-2027

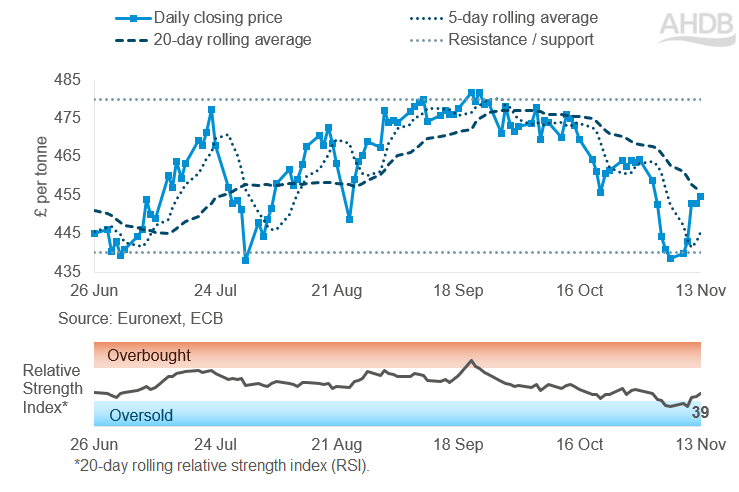
Figure 2. Paris rapeseed futures prices, May-2027 contract, in £/tonne

Paris rapeseed futures gained over the week, ending Friday above £445/t.  In £ per tonne, the May-2027 contract gained 3.7%.

The May-2027 contract is still below the 20-day rolling average but has surpassed the 5-day rolling average.

The solid line with markers in Figure 1 shows the May-2027 contract prices. The dashed line shows the 20-day rolling average, and the solid line shows the 5-day rolling average.

Since the start of October, sterling has strengthened against the euro. This has added further pressure to UK rapeseed values by lowering the sterling-equivalent value of Paris rapeseed futures.

Find out more about the graphs in this report and how to use them

Market drivers

Oilseed markets rose over the past week. They were driven primarily by the November USDA World Supply and Demand Estimates (WASDE), ongoing Russian and Ukrainian attacks, and Brazilian soyabean planting progress.

Chicago soyabean futures for May-2027 gained 3.0%. May-2027 Paris rapeseed futures were up 3.5%, and Winnipeg canola futures rose 3.7%.

However, nearby Brent crude fell 2.5%, ending the week at $95.80/barrel. This limited some of the gains in the oilseeds market.

The November WASDE raised US soyabean production by 331 Kt to 124.5 Mt. Higher yields in Minnesota, Iowa, South Dakota and Nebraska more than offset declines in Illinois, Kansas, Missouri and Arkansas. The estimate was still below the 125.1 Mt the trade expected.

The bigger crop was outweighed by a 681 Kt increase in exports to 46.8 Mt, so ending stocks fell to 8.2 Mt, well below the average trade expectation of 9.0 Mt.

Global changes were limited. Brazil’s soyabean crop was held at 186.0 Mt, with Argentina also unchanged at 50.0 Mt. World soyabean 2026/27 ending stocks were trimmed by 0.8 Mt to 123.5 Mt.

The tighter US balance sheet supported prices.

Brazil's 2026/27 soybean crop was 66% planted by early November, and 96% planted in Mato Grosso, the main producing state.

Brazil's crop agency, Conab, forecasts a crop of 181.6 Mt, up 0.7% on last year, which added downward pressure to the oilseed complex.

However, irregular rainfall and high temperatures linked to El Niño are keeping yield expectations cautious. The weather in the southern hemisphere is a key watchpoint going into 2027 for oilseed market sentiment.

Ongoing Russian attacks on Ukrainian infrastructure continue to limit Black Sea oilseed exports and push up freight costs.

Most recently, several companies have paused crushing after their refineries were hit. Prolonged outages could tighten global vegetable oil supply and support prices. 

Table 3. Global oilseed and oil futures prices

Futures marketContract monthPrice per tonneChange on week
Paris rapeseed May-2027 €544.25 +€18.50
Chicago soyabeans May-2027 $457.23 +$13.32
Chicago soyabean oil May-2027 $1,433.21 +$35.49
Brent crude oil* nearby $95.84 −$2.48

*Brent crude oil price per barrel
n/a = not available
n/c = no comparison available

UK delivered rapeseed prices

The delivered price for rapeseed into Erith in November was £462.50/t in Friday’s survey, up £19.00/t from the previous week.

The market support also fed into new crop values, with Harvest 2027 delivered prices at £440.00/t for Erith, up £12.00/t week-on-week.

Table 4. UK delivered rapeseed prices

Delivery specificationDelivery monthPrice per tonneChange on week
Erith May-2027 £472.00 +£19.50
Liverpool May-2027 n/a n/a
East Anglia May-2027 n/a n/a

n/a = not available
n/c = no comparison available

Extra information

UK trade data

HMRC released UK trade data for September 2026. UK wheat imports totalled 216 Kt in September, bringing imports in the first three months of the 2026/27 season (July–September) to 559 Kt. This is 90 Kt lower than the 649 Kt imported during the same period last season.

UK maize imports fell to 58 Kt in September. However, combined July, August and September imports totalled 539 Kt, compared with 457 Kt over the same period in 2025/26.

UK oat imports have risen. Imports in September 2026 were 17 Kt, taking the UK’s imports in the 2026/2027 season so far to 22 Kt. This is 3 Kt more than was imported in the whole 2025/2026 season.

UK total oilseed imports for September 2026 fell 22% year-on-year to 256 Kt. This brings the 2026/2027 season total so far to 772 Kt, down 15% from 903 Kt last season. Soyabean imports have seen growth, increasing 23% on the year, whereas oilseed rape imports have reduced 29%.

Early Bird Survey

The 2026 AHDB Early Bird Survey results give insight into plantings and planting intentions for harvest 2027.

The survey shows the oilseed rape area is forecast to rise 28% to a provisional 415 Kha. This would be the largest since 2019, helped by better margins and improved 2026 yields.

Meanwhile, winter cereal areas are broadly steady after good drilling conditions, with wheat up 1% to 1,664 Kha.

However, the spring barley area is forecast to fall 11% to 531 Kha, the lowest since 2006. The total oat area is also expected to be down 18% from 2026. Pulses, down 20%, also lose ground, mostly to oilseed rape.

Final figures and regional/country breakdowns are due in mid-December.

Northern Ireland

Table 5. Delivered prices into Belfast*

Delivery specification**Delivery monthPrice per tonneChange on week
Feed barley  - spot Spot £209.50 n/c
Feed barley  - forward Feb-2027 £214.50 +£5.50
Feed wheat  - spot Spot £223.00 n/c
Feed wheat  - forward Feb-2027 £223.50 n/c

*Prices provided for indicative purposes. 

**Basis is imported/home-grown.

n/c = no comparison


Sign up to receive the latest information from AHDB

While AHDB seeks to ensure that the information contained on this webpage is accurate at the time of publication, no warranty is given in respect of the information and data provided. You are responsible for how you use the information. To the maximum extent permitted by law, AHDB accepts no liability for loss, damage or injury howsoever caused or suffered (including that caused by negligence) directly or indirectly in relation to the information or data provided in this publication.

All intellectual property rights in the information and data on this webpage belong to or are licensed by AHDB. You are authorised to use such information for your internal business purposes only and you must not provide this information to any other third parties, including further publication of the information, or for commercial gain in any way whatsoever without the prior written permission of AHDB for each third party disclosure, publication or commercial arrangement. For more information, please see our Terms of Use and Privacy Notice or contact the Director of Corporate Affairs at info@ahdb.org.uk  © Agriculture and Horticulture Development Board. All rights reserved. 

×