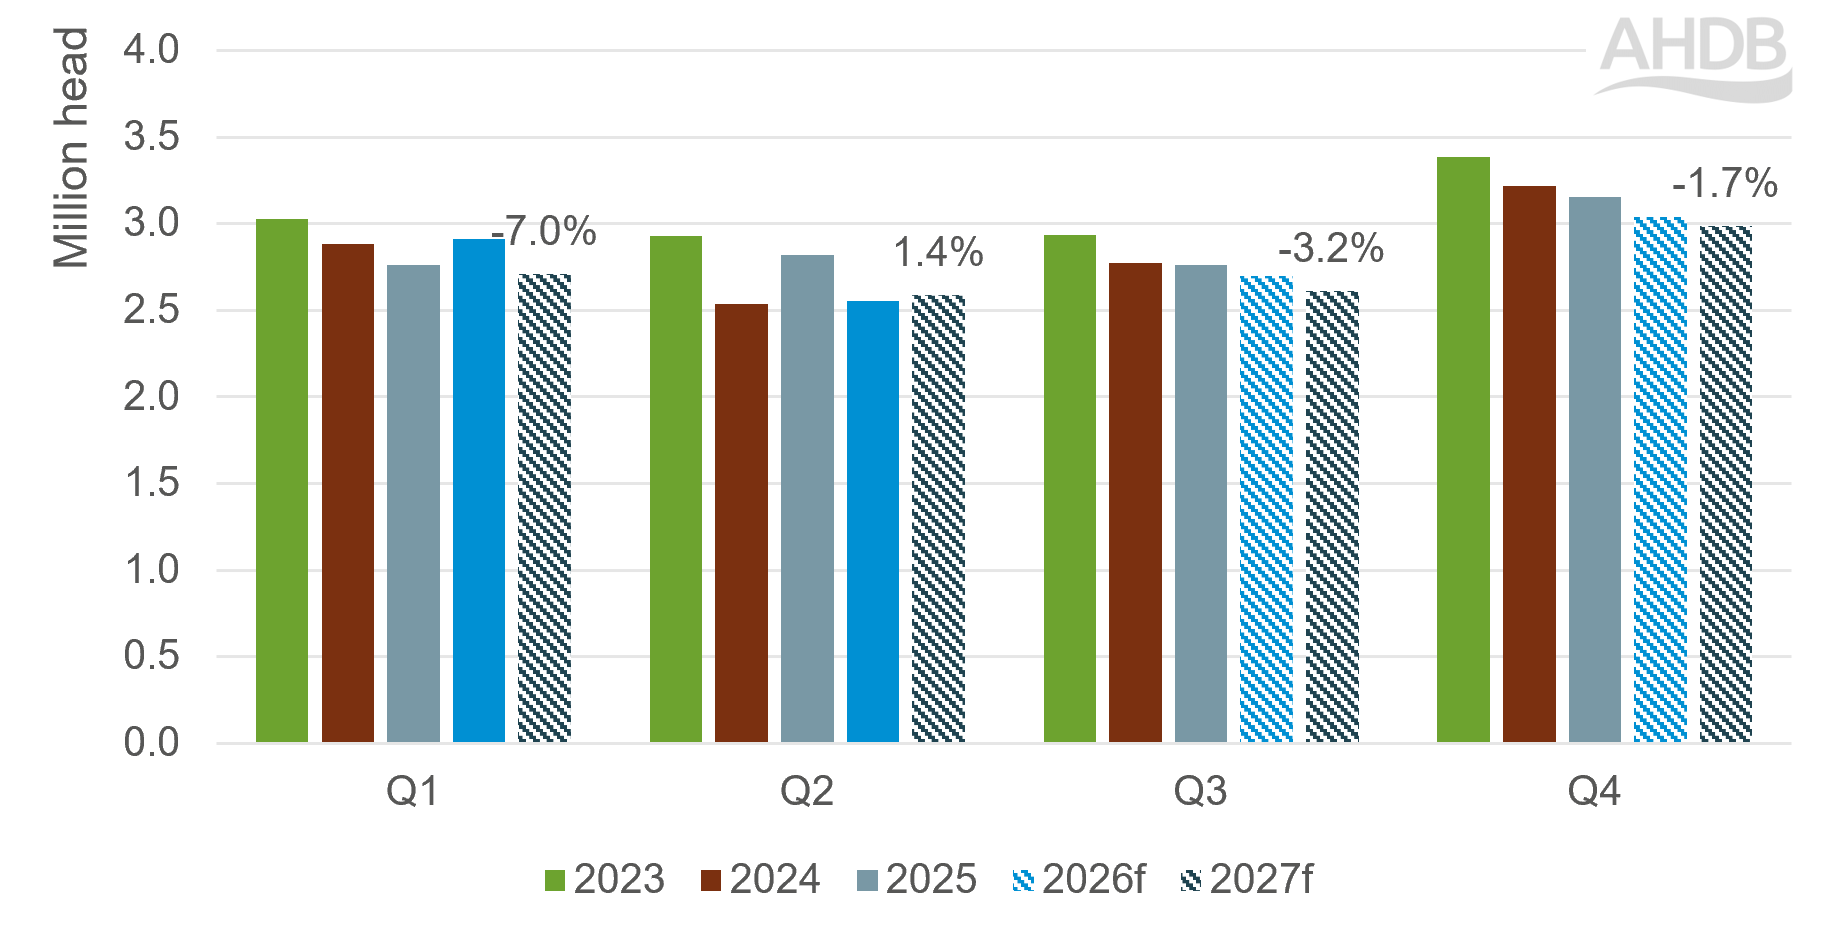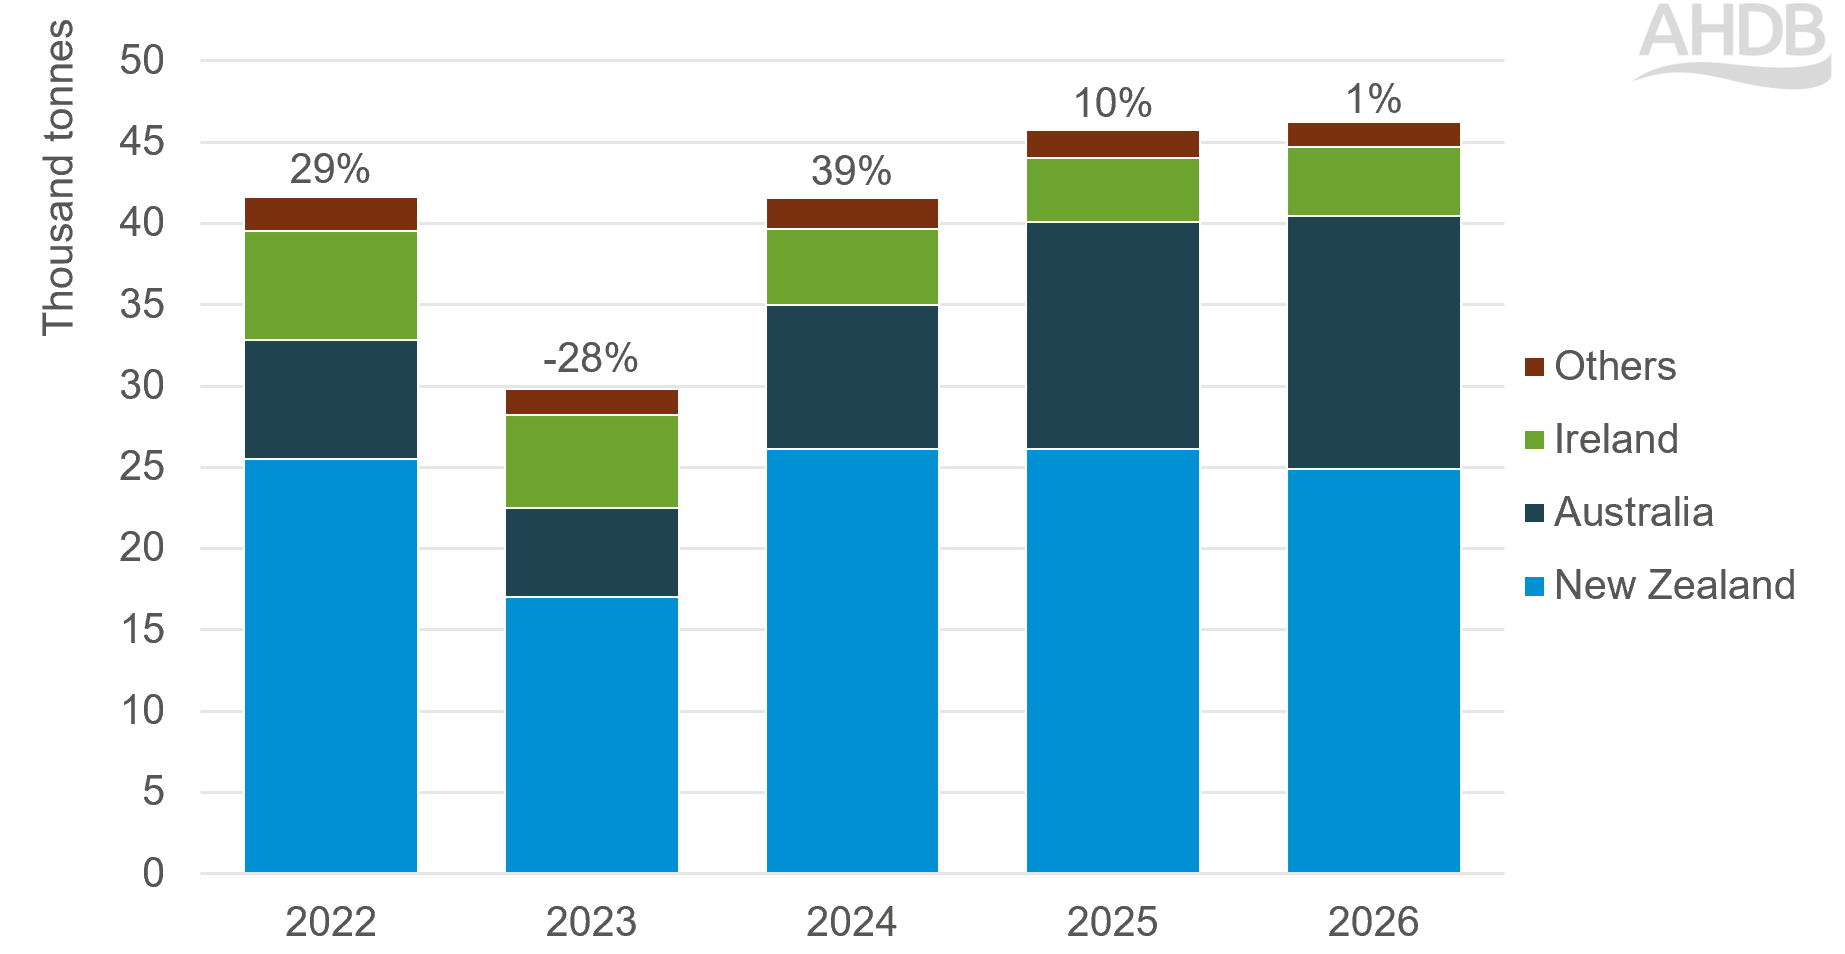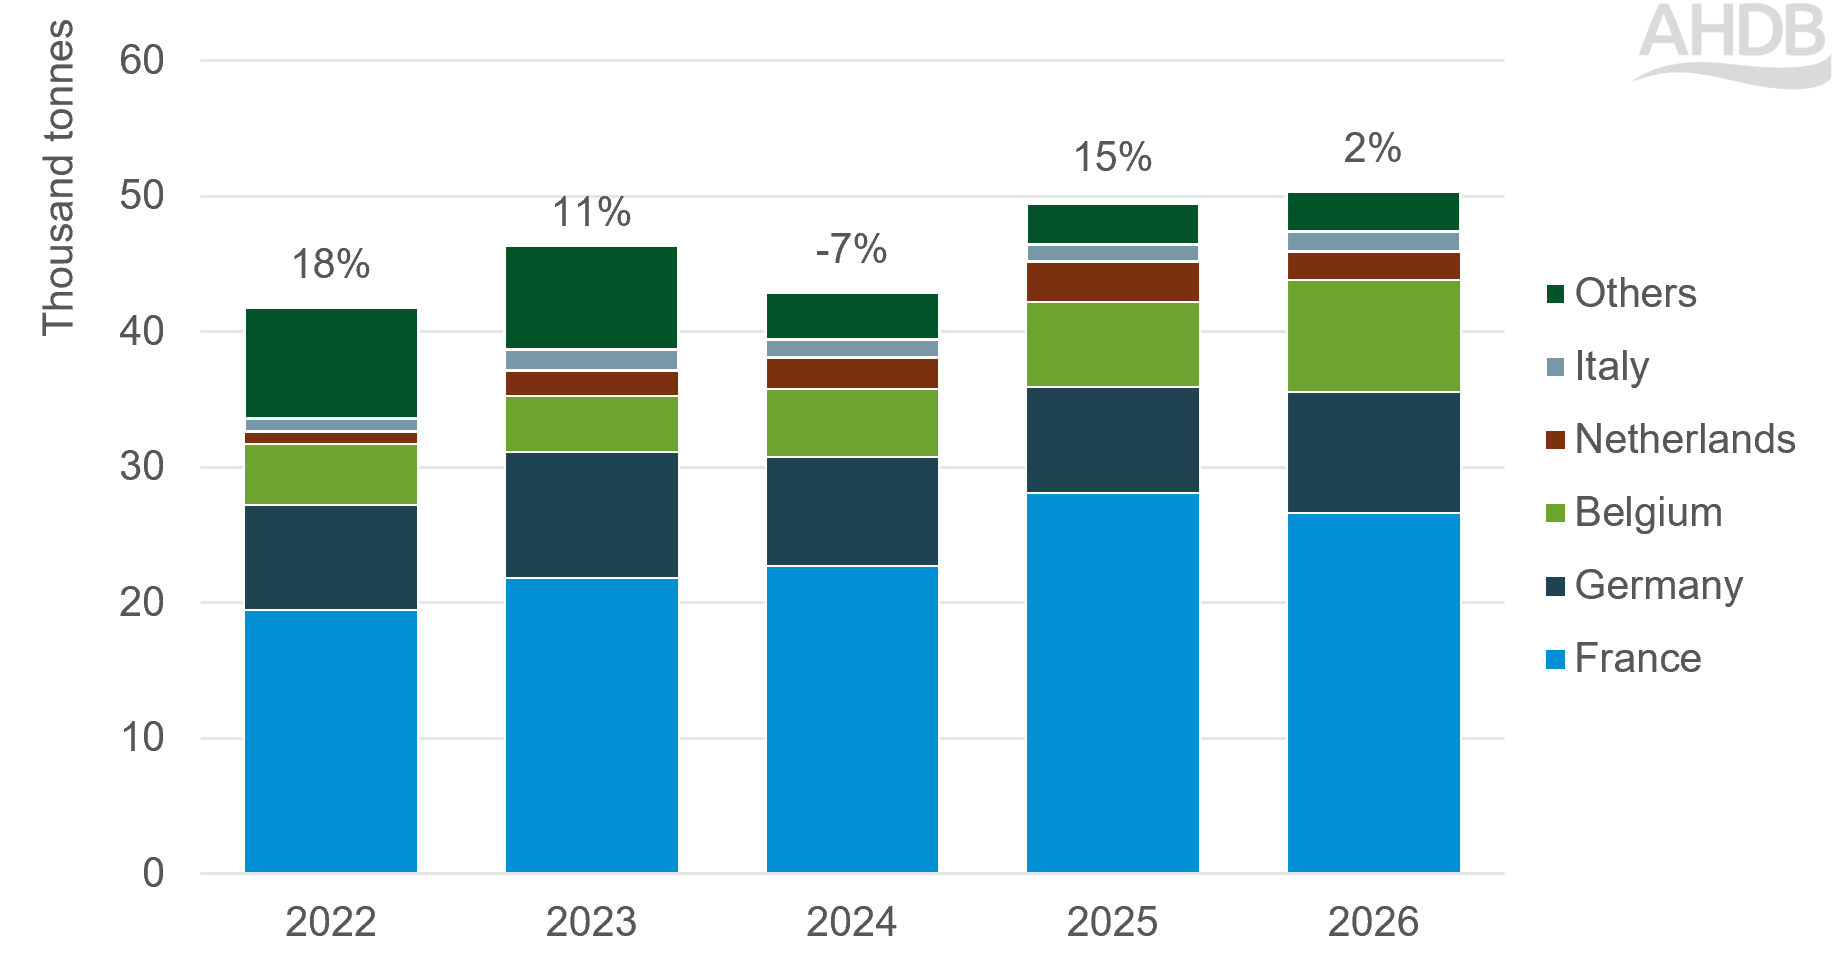
Lamb market outlook

October 2026

Key points

  • UK sheep meat production is forecast to continue declining through 2027 as lower slaughter numbers and a contracting breeding flock tighten domestic supply.
  • Lamb demand is expected to remain under pressure from weak consumer confidence and cost-of-living challenges, with volumes forecast to fall in both 2026 and 2027.
  • Strong EU import demand should continue to support UK exports, although lower UK production may limit growth opportunities.
  • Import growth is expected to remain constrained by tighter Australian and New Zealand supplies, narrowing price differentials and subdued UK demand.
  • Supply-side tightening in the UK, EU and Southern Hemisphere is expected to offer support to lamb prices through 2027.
  • Bluetongue remains a downside risk to production forecasts, with potential impacts on ewe fertility and future lamb crops, although the scale of impact will depend on disease spread and vaccination uptake. We include a production impact scenario in this outlook.
Image of staff member Hannah Clarke

Hannah Clarke

Lead Analyst (Red Meat)

See full bio

Overview

The UK lamb market has remained resilient through 2026. Lower domestic production and reduced sheep meat availability across Europe have underpinned prices and supported export demand.

At the same time, tighter supplies from key Southern Hemisphere exporters have helped limit import pressure, although consumer demand has remained tempered by ongoing cost-of-living concerns. As a result, supply-side factors have been the dominant influence on the market so far this year.

The outlook for 2027 and 2028 reflects a tension between constrained supply and uncertain demand. Limited availability of lamb in the UK and some overseas markets could provide underlying price support, but softer consumer demand, changing import and export competitiveness, and uncertainty around disease and the wider economy will continue to shape market direction.

Sheep price outlook

Domestic sheep availability is expected to remain tight in 2026 and 2027. Bluetongue is expected to modestly contribute to further tightening.

While UK demand is subdued so is global supply, with Southern Hemisphere and EU production back. A key downside price risk may be felt indirectly from adjusting global trade flows, for example with recent announcements from the US around their lamb import safeguard investigation.

Whilst the UK has limited direct exposure to the US market, any restrictions on Australian and New Zealand lamb could cause this product to be redirected to the UK or UK export markets.

The balance of risks currently remains supportive for GB lamb prices. Export demand is being underpinned by tightening EU supplies, while global lamb availability is becoming less abundant as production in New Zealand falls and Australia rebuilds its flock.

Although consumer demand remains fragile, supply-side tightening is expected to outweigh demand weakness, supporting prices through 2027.

Domestic supply and production outlook

Production constrained during the first half of 2026

During the first half of 2026, UK clean sheep slaughter totalled 5.46 million head, 2% (116,000 head) lower than the same period a year ago, according to Defra figures.

Quarterly slaughter totals were more in-line with those seen in 2024. A slightly larger old season lamb (OSL) carryover pushed total Q1 lamb slaughter up by 5% on the year, while a tighter June contributed to kills being back by 9% year-on-year in Q2.

Sheep meat production 2026/27

Lamb supply is expected to tighten further during the current 2026/27 season.

For the second half of 2026, lamb slaughter is expected to total 5.74 million head, down 3% year-on-year.

A further reduction in OSL carryover is forecast to reduce lamb slaughter during the first half of 2027 by 3% overall, with the year-on-year decline weighted in Q1. Supply reductions are expected to continue through the second half of 2027.

Figure 1: Actual and forecast UK sheep meat production 2023 - 2027

Source: Defra, AHDB calculations and forecasts in hashed bars

Figure 1 shows trends in UK sheep meat by quarter since 2023, with forecasts for 2026 Q3 and Q4 and 2027.

Average sheep carcase weights have been marginally heavier than last year on average, according to Defra data. This has likely been influenced by more attractive concentrate feed prices. GB sheep feed production increased during July and August.

Assuming continued trends in carcase weights, this brings the forecast for total UK sheep meat production for 2026 to 269,000 tonnes, down 1.3% versus 2025.

Sheep meat production 2027/28

Defra reports that the UK breeding ewe flock stood at 13.01 million head on 1 December 2025. However, Welsh figures used within this total remain provisional at time of writing.

As such, we estimate that the long-term gentle contraction in breeding ewe numbers has continued, with the UK flock shrinking by 1% year-on-year to 12.98 million head at 1 December 2026.

Clean sheep slaughter in 2027 is forecast at 10.89 million head, down 2.7% from the 2026 forecast. Combined with an expectation of lower adult sheep slaughter, this reduces sheep meat production by 2.4% to 262,000 tonnes.

Supply and production: Bluetongue scenario

Overview

At the time of writing, on 12 October, there were 3,338 farms (premises) with confirmed cases of bluetongue (BTV-3) or unspecified serotype in the UK in the 2026-27 season. There is significant concern across the industry about the potential impact of bluetongue on individual farms and domestic sheep production.

Keep up to date with the latest information about Bluetongue.

Assessing how the bluetongue outbreak will shape the sheep supply outlook is challenging, as much remains unknown about the impact of the disease and levels of vaccination. To assess the potential impact on UK sheep production, we have developed a “likely” bluetongue scenario.

The scenario assumes that the geographic spread of bluetongue is concentrated in the South West, West Midlands, East Midlands, North West, Yorkshire (South and West) and Wales. It assumes that 20% of sheep within 25% of flocks in these areas become infected, equivalent to 5% of the total sheep flock in the affected area. Mortality rates are assumed to be 25%, with fertility falling by 30% among infected ewes.

There is limited empirical evidence on likely mortality and fertility impacts under UK conditions. These assumptions have therefore been informed by extensive industry engagement and represent our assessment of a plausible impact. We have also tested a range of scenarios using higher and lower mortality and fertility assumptions. While these change the scale of losses at farm level, they do not materially alter the direction of the national production outlook presented here.

Production impacts

Modelling the above scenario, UK sheep meat production reduces more over the next couple of years compared to the “baseline forecast” outlined above. Whilst bluetongue could have a devastating impact on affected farms, when it is grossed up to the national level the overall impact is modest.

In this scenario, clean sheep slaughter is expected to fall by a further 83,000 head before Christmas (approximately 1% of kill), while a further 103,000 breeding ewes are lost compared to the baseline forecast (approximately 1% of the national ewe flock). This means that production reduces by a further 2,000 tonnes in 2026 compared to the baseline forecast.

The more significant impact is on fertility rates and thus the size of the lamb crop born in 2027. As a result, lamb slaughter is forecast to fall by an additional 95-150,000 head per year compared to the baseline forecast.

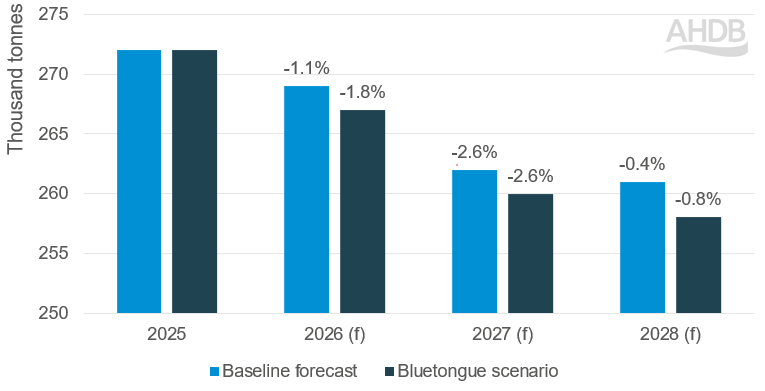
Assuming average carcase weights, this reduces sheep meat production by a further 2-3,000 tonnes per year compared to the baseline forecast. The differences are shown in Figure 2.

Figure 2: Actual and forecast UK sheep meat production in the baseline forecast and bluetongue scenario for 2025 – 2028, with year-on-year change

Source: Defra, AHDB calculations and forecasts

A significant risk to this scenario is vaccination uptake. Data on vaccines bought or ordered is not published by government. We have assumed that vaccine update has been modest in 2026 and will only become widespread in the 2027/28 season. A quicker uptake of vaccination would shift sheep production much closer to our baseline forecast.

Trade outlook

Imports

In the first seven months of 2026 (Jan-Jul) total sheep meat imports (incl. fresh, frozen and processed) totalled 46,300 tonnes (product weight). This was 1% more than the same period of 2025, with growth in imports from Australia (+11%) and Ireland (+8%) outweighing losses from New Zealand (-5%).

Despite the modest volume gain, the value of these imports was up by 18% year-on-year to £318 million.

Figure 3. UK sheep meat import volume by supplier for the year-to-date (Jan-Jul)

Source: UK HMRC via Trade Data Monitor

Figure 3 shows trends in UK sheep meat imports from key suppliers between 2022 and 2026.

While volume growth has been modest so far in 2026, the proportion of UK sheep meat supply made up by imports has increased. Imports are expected to remain an important supply element going forward.

While domestic lamb supply is forecast to tighten, constrained global supply, price competitiveness and subdued domestic consumer demand may limit import growth. Consumer purchasing is expected to pick up seasonally ahead of Christmas, but demand will remain subdued generally year-on-year.

Southern hemisphere availability is expected to remain tight, with industry outlooks pointing to lower production in New Zealand and Australia through 2027. Lower supply in these regions have supported prices and narrowed the advantage to UK lamb.

Overall, we forecast sheep meat imports to rise by 1% year-on-year for the full year of 2026. Volumes are expected to stay broadly steady in 2027.

Exports

Sheep meat exports began the year strongly but have generally weakened as the year has progressed.

For the year-to-date (Jan-Jul), UK sheep meat exports (incl. fresh, frozen and processed) totalled 50,400 tonnes (product weight). This was 2% higher than the same period in 2025, with growth to several European destinations including Belgium (+32%), Germany (+15%) and Italy (+15%). Volumes shipped to France fell by 5%. Growth was also noted to several non-EU countries, including Saudi Arabia.

These exports were valued at £428.7 million, up 13% year-on-year.

Figure 4. UK lamb export volumes by destination, YTD (Jan-Jul)

Source: UK HMRC via Trade Data Monitor

Figure 4 shows trends in UK lamb exports to key destinations from 2022 to 2026.

Exports have continued to make up an increasing share of UK production over recent years. For the full year of 2026, UK lamb exports are forecast to grow modestly, by approximately 3% year-on-year.

Export prospects remain broadly positive through 2027. Tight European sheep meat supplies should continue to underpin demand for UK exports, but lower UK production is likely to be a key constraint on growth. The biggest upside risk would be a meaningful reduction in UK-EU trade friction through the SPS agreement, although exact timing remains subject to ongoing negotiations. The main downside risk would be increased competition from diverted Southern Hemisphere product if current global trade flows are disrupted, for example to the US.

Domestic consumption outlook

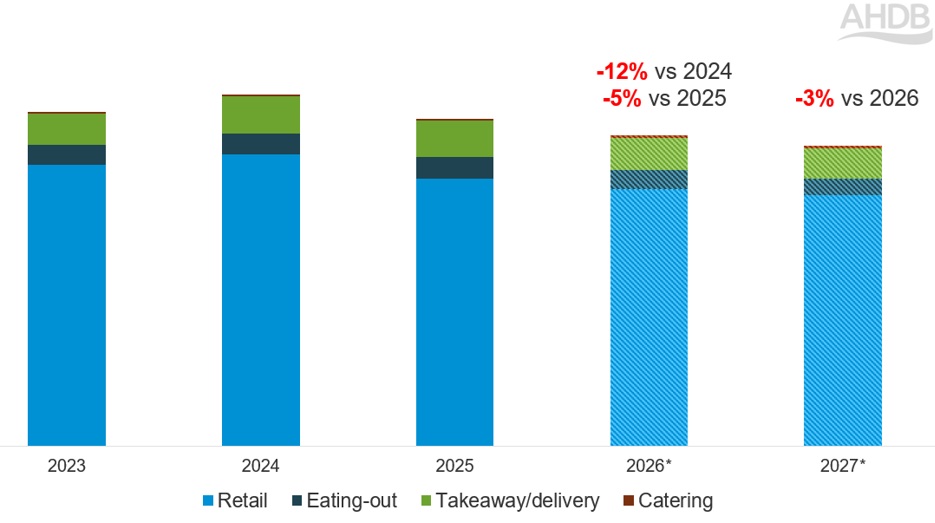
In the past 52 weeks, higher average prices have seen retail lamb spend grow +4.0%1 and out-of-home (OOH) lamb spend decline -6.8%2 year-on-year2. These higher prices have led to a retail volume decline of -2.2%1 and an OOH volume decline of -16.4%3.

Our revised forecast for total UK lamb consumption volumes in 2026 is -5% versus 2025.

For 2027, we predict consumer confidence to remain muted. Rising food inflation and energy costs will add pressure to household incomes, as detailed in our economic outlook. Consumers are likely to make careful spending decisions, focusing on getting the best value for money. As lamb continues to be viewed as a premium protein, we forecast total lamb consumption volumes will decline by -3% in 2027.

For further information and latest trends for lamb, visit our lamb retail dashboard and our foodservice dashboard.

Figure 5: Actual and forecast volumes of lamb sold in the UK

Source: AHDB volume estimates for UK based on Worldpanel by Numerator UK retail and OOH data. *2026 and *2027 figures are AHDB estimates

Figure 5 shows volumes in 000kg for lamb sales in UK split by retail, eating-out, takeaway/delivery and catering. Actual volumes are shown for 2023 through to 2025. AHDB estimated volumes are shown for 2026 and 2027. Over the 5-year period, retail is consistently the largest component. AHDB estimates volumes for 2026 will be -5% in decline versus 2025 and -12% in decline versus 2024. AHDB estimates volumes for 2027 will be -3% in decline versus 2026.

Retail demand

Lamb is expected to remain a treat protein, with demand focused around key occasions such as Easter, Eid and Christmas. We may see increases in lamb roasting for these occasions as an indulgent treat. Older and more affluent consumers are expected to remain loyal to the category, however this will depend on their financial situations. Other shoppers may gradually switch to cheaper proteins.

Promotions are likely to remain important for lamb as shoppers continue to look for value for money. Lamb steaks and lamb burgers could perform well as they are currently a cheaper alternative to their beef counterparts. Lamb mince, the cheapest primary lamb cut, may also see gains. The continued focus on healthy eating, including high protein diets and less processed foods, is likely to encourage more scratch cooking, and as a result, dishes such as Shepard’s pie may appeal to consumers.

We expect that the weather will have an impact on demand for lamb throughout the year. A hot, dry summer could limit lamb purchases, as it is not as strongly linked to barbecues and picnics as some other proteins. However, colder and wetter weather later in the year could increase the demand for lamb through warm and comforting meal occasions.

Out-of-home demand

We expect volumes to remain under pressure as consumers continue to save eating out for special occasions, with many choosing instead to enjoy a ‘big-night-in’ instead. When they do choose to eat out, shoppers are likely to focus on options that feel like a treat while still offering value for money.

Takeaway volumes, which are the most important channel for lamb in foodservice, are expected to continue their gradual decline, although this may begin to level off towards the middle of 2027. Kebab sales are likely to remain under pressure as consumers move away from late-night and post-drinking occasions, which traditionally support the meals popularity. However, the Women's FIFA World Cup during June and July 2027 could provide a boost to takeaway and delivery sales as consumers watch and celebrate matches at home.

How might the lamb demand outlook be improved?

The lamb demand outlook might be further boosted, if the industry:

  • Maximise promotional activity around key seasonal occasions, such as Easter, Eid and Christmas, helping shoppers see lamb as an affordable treat for family meals and celebrations.
  • Highlight lamb cuts that offer good value, encouraging consumers to keep eating lamb despite ongoing budget pressures.
  • Provide simple recipe inspiration that supports scratch cooking, showcasing lamb as a natural source of protein that can be used in everyday family meals.
  • Hot weather provides an opportunity to promote lamb products as a more luxury or indulgent replacement for other more typical barbeque protein sources.
  • Promote lamb's role in comforting, home-cooked dishes during colder periods, when consumers are looking for warming meal options.
  • Work to keep lamb visible on menus out-of-home, reinforcing its role as a premium and treat-led choice.
  • Build consumer trust in British lamb by continuing to communicate the industry's strengths in animal welfare, environmental stewardship and farming expertise.

We have a range of marketing activities planned for the year, including the Let’s Eat Balanced campaign. Please visit our marketing pages for more information.

For more insight around consumer demand, visit our retail and consumer pages.

Image of staff member Emma Wantling

Emma Wantling

Retail and Consumer Insight Manager

See full bio


Sign up to receive the latest analysis and forecasts from AHDB


While AHDB seeks to ensure that the information contained on this webpage is accurate at the time of publication, no warranty is given in respect of the information and data provided. You are responsible for how you use the information. To the maximum extent permitted by law, AHDB accepts no liability for loss, damage or injury howsoever caused or suffered (including that caused by negligence) directly or indirectly in relation to the information or data provided in this publication.

All intellectual property rights in the information and data on this webpage belong to or are licensed by AHDB. You are authorised to use such information for your internal business purposes only and you must not provide this information to any other third parties, including further publication of the information, or for commercial gain in any way whatsoever without the prior written permission of AHDB for each third party disclosure, publication or commercial arrangement. For more information, please see our Terms of Use and Privacy Notice or contact the Director of Corporate Affairs at info@ahdb.org.uk  © Agriculture and Horticulture Development Board. All rights reserved. 

×