Arable Market Report – 5 October 2026

Monday, 5 October 2026

This week's view of grain and oilseed markets, including a summary of both UK and global activity.

Grains

UK feed wheat futures (Nov-26)

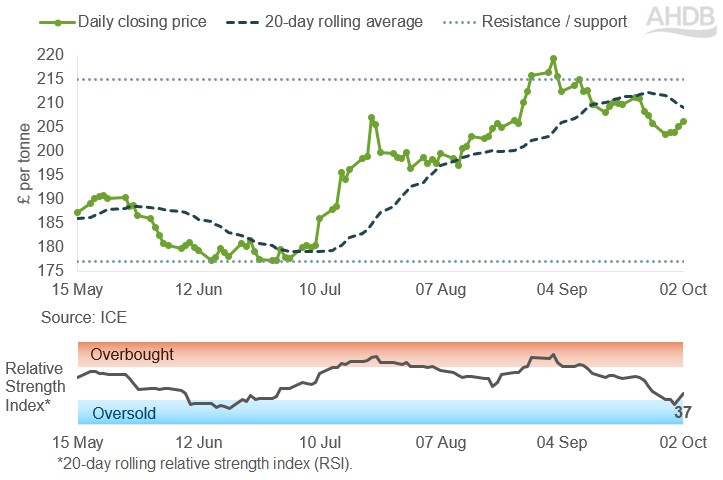
Figure 1. UK feed wheat futures prices, Nov-26 contract (£/tonne)

UK wheat futures gained with Paris milling wheat futures last week. The Nov-26 contract closed at £206.25/t, gaining £0.50/t week-on-week.

The Nov-26 contract prices are shown by the solid line with markers in Figure 1.

Prices have recently moved below the 20-day moving average and momentum indicators have weakened. While this suggests near-term downside pressure, the market has not yet entered oversold territory. As such, there’s a risk of further consolidation unless fresh fundamental support emerges.

Find out more about the graphs in this report and how to use them

Market drivers

Global grain markets ended mixed across the week. The US wheat and maize markets ended down, while the Paris wheat market gained across the week.

This mix in market momentum was due to USDA stocks data, geopolitics, global demand, and US harvest pressure. While the market looks generally well supplied globally, trade disruptions and uncertainty underpin global prices.

Most of the negative sentiment in the US market followed the USDA's latest Grain Stocks report. It showed 1 September maize stocks at 53.2 Mt, up 35% year on year and above trade expectations.

This, combined with a stronger US dollar and harvest pressure, weighed on the US market, despite generally robust global demand.

Last week Saudi Arabia launched a tender for 535 Kt of wheat. Traders viewed it as evidence that lower prices are encouraging buyers back into the market. The kingdom cancelled a previous tender due to high prices. This provided some support to Paris wheat futures.

Further to that, ongoing disruption to Black Sea trade continued to underpin prices in Europe. Diplomatic efforts showed little progress towards restoring normal shipping routes. Russia's rejection of proposals for a truce in Black Sea attacks maintained concerns over export disruption.

The Ukrainian farm minister warned that winter wheat plantings for the 2027 harvest could fall by 17% due to ongoing export difficulties caused by the conflict. Although September grain and vegetable oil exports improved month on month, shipments remain well below potential capacity. This raises concern over income and future Ukrainian wheat production and export availability.

Attention now turns to this week’s USDA World Agricultural Supply and Demand Estimates (09 October). They are expected to provide clearer direction on US crop sizes for maize and soyabeans and global balance sheets.

Table 1. Global grain futures prices

Futures marketUK feed wheatParis milling wheatChicago wheatChicago maize
Contract month Nov-26 Dec-26 Dec-26 Dec-26
Price (per tonne) £206.25 €241.50 $250.93 $195.96
Change on week +£0.50 +€4.75 -$7.44 -$12.01

UK delivered cereal prices

Delivered feed wheat into Yorkshire, Nov-26, was quoted at £218.50/t last Thursday, down £2.00/t on the week. This equated to a £13.25/t premium to UK feed wheat futures (Nov-26).

Bread wheat to be delivered into the North West in November was quoted at £232.50/t. This equated to a £27.25/t premium to the Nov-26 UK feed wheat futures based on Thursday’s close. 

Meanwhile, bread wheat into Yorkshire in November was quoted at £229.00/t, a £23.75/t premium, and into Northants in Nov-26 was quoted at £221.50/t, a £16.25/t premium to UK feed wheat futures.

Table 2. UK delivered cereal prices

Delivery specificationN'hants bread wheatE. Anglia feed wheatYorkshire feed wheatE. Anglia feed barley
Delivery month Nov-26 Nov-26 Nov-26 Nov-26
Price (per tonne) £221.50 n/a £218.50 n/a
Change on week n/c n/a -£2.00 n/a

n/a = not available

n/c = no comparison available.

Rapeseed

Paris rapeseed futures in £/t (Nov-26)

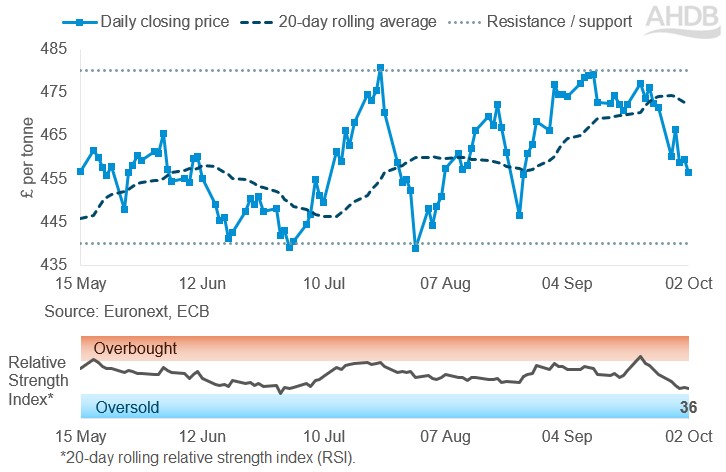
Figure 2. Paris rapeseed futures prices, Nov-26 contract (£/tonne)

Nov-26 Paris rapeseed futures fell 3.2% in £/t last week to approx. £456.50/t. This was a bigger fall than in euros as sterling rose against the euro.

The Nov-26 contract fell further below the 20-day rolling average, which had previously acted as a support line. A support line is a level that prices can find it harder to move below.

The solid line with markers shows the Nov-26 prices in Figure 2, while the dashed line shows the 20-day rolling average.

The Relative Strength Index (RSI) also declined from 53 on 25 September to 36 on 2 October. The fall in the RSI reflects the change in momentum in Nov-26 prices.

The Nov-26 contract will stop trading on 30 October. In a futures contract’s final weeks of trading, it can become less reliable as an indicator of supply and demand, and so physical prices.

So, in next week’s report, we will show the prices for the May-27 contract. The May-27 futures fell by less than the Nov-26 contract last week, down 1.4% to approx. £425.75/t.

Find out more about the graphs in this report and how to use them

Market drivers

Nov-26 Rapeseed prices fell 2.1% last week due to a mix of constrained demand and global price pressure. Low water levels in European rivers continue to hamper logistics and so short-term rapeseed crush demand (Agritel).

Nov-26 Chicago soyabeans fell 3.1%, while Nov-26 Winnipeg canola fell 1.6%.

A sharply stronger US dollar and expectations for higher US soya bean supplies led to the weekly fall in Chicago prices. Selling by speculative traders also added to the downward trend.

StoneX increased its forecast of the US soya bean crop by 2.8 Mt to 126.5 Mt as it expects a higher average yield. StoneX’s latest estimate is now over 3.0 Mt higher than the USDA’s September estimate of the 2026 crop. It would also be 10.5 Mt larger than last year’s crop.

The USDA releases its next estimate of the US crop, alongside updated estimates of world supply and demand on Friday, at 5pm.

But wet weather continued to be a concern for harvesting soya beans in the USA and limited some of the pressure on prices. Low end-of-year stocks, plus the harvest delays, have reportedly reduced crushing in affected areas.

The canola harvest in Canada is also advancing but is still behind recent years’ progress after wet weather.

Forecasts show a drier week ahead for much of the USA and Canada.

Crude oil prices remain volatile. Despite falling in the first part of last week, the Dec-26 contract ended the week 4.9% higher than on 25 September at $102.25/barrel. Prices lifted after the USA said it was considering strengthening its military presence in the Middle East.

Longer term, vegetable oil supplies remain a watch point. Exports of sunflower oil from the Black Sea are still limited by the conflict. Plus, recent dry weather due to El Niño poses a risk to supplies in 2027.

The Indonesian Palm Oil Association forecasts a 4% fall in production in 2027.

Table 3. Global oilseed and oil futures prices

Futures marketParis rapeseedChicago soya beansChicago soya bean oilBrent crude oil*
Contract month Nov-26 Nov-26 Dec-26 nearby
Price (per tonne) €536.75 $469.63 $1,512.80 $102.25
Change on week -€11.25 -$14.97 +$17.20 +$4.81

*Brent crude oil price per barrel

UK delivered rapeseed prices

On Friday, the delivered rapeseed price for Erith in November was £472.50/t, down £7.00/t from 25 September. The fall for the same month delivered to Liverpool was £6.50/t to £472.00/t.

But there were smaller declines in prices to both locations in February and May 2027, echoing the pattern in the Paris futures market.

The February delivered price declined week-on-week by £2.00/t for Erith and £1.50/t for Liverpool. The May price fell £1.00/t for Erith and just £0.50/t for Liverpool.

The price for harvest-27 was £458.00/t in both Erith and Liverpool. While no week-on-week comparison is available, Friday’s price was £3.50/t higher than the price two weeks ago.

Table 4. UK delivered rapeseed prices

Delivery specificationErithLiverpoolEast Anglia
Delivery month Nov-26 Nov-26 Nov-26
Price (per tonne) £472.50 £472.50 £471.00
Change on week -£7.00 -£6.50 n/c

n/c = no comparison available

Extra information

Last Thursday, AHDB released the cereals used to produce GB compound feed and used by the human and industrial sectors in August.

GB animal feed compounders used 842.9 Kt of raw materials in August 2026, down 2.0% year-on-year. Cumulative usage for July-August totalled 1.67 Mt, 3.8% lower than the same period last season.

UK flour millers used 422.9 Kt of wheat in August 2026, up 0.8% year-on-year. Over the first two months of the 2026/27 season (July-August), total wheat milled reached 852.2 Kt, down 7.1% compared with the same period last season. The decline was driven by lower imported wheat usage, while home-grown wheat milling increased year-on-year in August.

On Thursday 8 October, Defra will release its provisional estimates of English wheat, barley, oat and oilseed rape production in 2026.

The Scottish Government will also release the results of the June Survey of Agriculture on 8 October, showing the cropped area for harvest 2026.

Northern Ireland

Due to insufficient quotes, we are unable to publish delivered Belfast cereals prices for 02 October 2026.


Sign up to receive the latest information from AHDB

While AHDB seeks to ensure that the information contained on this webpage is accurate at the time of publication, no warranty is given in respect of the information and data provided. You are responsible for how you use the information. To the maximum extent permitted by law, AHDB accepts no liability for loss, damage or injury howsoever caused or suffered (including that caused by negligence) directly or indirectly in relation to the information or data provided in this publication.

All intellectual property rights in the information and data on this webpage belong to or are licensed by AHDB. You are authorised to use such information for your internal business purposes only and you must not provide this information to any other third parties, including further publication of the information, or for commercial gain in any way whatsoever without the prior written permission of AHDB for each third party disclosure, publication or commercial arrangement. For more information, please see our Terms of Use and Privacy Notice or contact the Director of Corporate Affairs at info@ahdb.org.uk  © Agriculture and Horticulture Development Board. All rights reserved. 

×