Arable Market Report – 28 September 2026

Monday, 28 September 2026

This week's view of grain and oilseed markets, including a summary of both UK and global activity.

Grains

UK feed wheat futures (Nov-26)

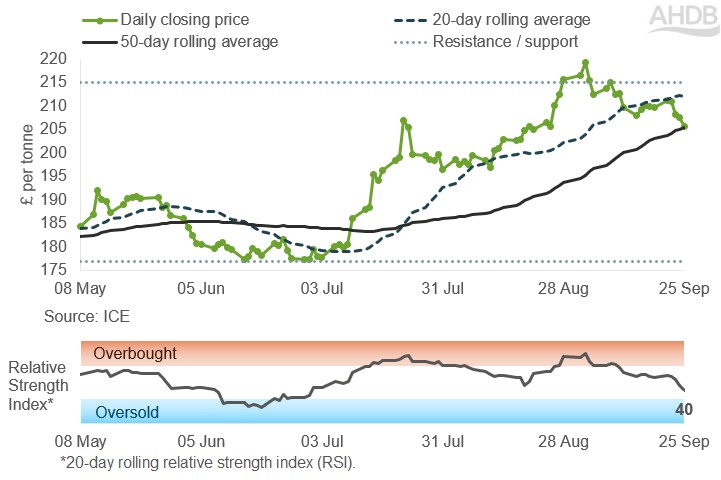
Figure 1. UK feed wheat futures prices, Nov-26 contract (£/tonne)

A graph showing UK feed wheat futures

UK wheat futures followed the pressure from the global grain market, with the Nov-26 contract closing at £205.75/t, down £4.00/t week-on-week (Figure 1).

The UK feed wheat futures price has fallen below the 20-day moving average and down towards the 50-day moving average.

Meanwhile, the Relative Strength Index (RSI) has slipped to 40. This indicates the momentum has weakened but the market is not yet oversold.

In Figure 1, the solid line with markers shows the Nov-26 prices. The 20-day rolling average is the dashed line, and the 50-day rolling average is the solid line with no markers.

If prices break below the 50-day moving average, traders could interpret this as confirmation that the uptrend from July through August is losing strength.

The next focus would likely be whether the 50-day average acts as support line or whether a break below it leads to a move towards the next support level near £177/t.

Market drivers

Global grain markets were mixed last week, with price action driven by a changing geopolitical landscape. Market fundamentals were largely pushed into the background.

Global wheat remained under pressure, as traders focused on diplomatic efforts to ease disruptions to Black Sea exports. Talks involving Ukraine, Turkey, India, Egypt and other Middle Eastern countries are seeking to restore shipping. Meanwhile, Turkey has submitted proposals to Moscow on maritime security.

The possibility that Russia could rapidly restart much of its Black Sea and Sea of Azov terminal capacity if a ceasefire were reached added to the pressure on prices.

Dec-26 Paris wheat futures fell 2.0% over the week, with Dec-26 Chicago wheat down 1.5%.  This was despite no substantive negotiations or agreements currently being reported.

Maize prices found modest support for most the week from the Trump-Xi meeting in Washington and the potential for changes to agricultural tariffs.

But maize prices weakened after the US-China summit didn’t lead to immediate commitments for China to buy more US crops. This weakness also weighed on wheat prices.

Prices later recovered modestly as pre-weekend buying emerged, and Dec-26 Chicago maize futures ended the week up 0.1%.

This morning, news emerging from the US-China summit indicates that China plans to reduce tariffs on a broad range of US agricultural products.

The list includes maize, wheat, sorghum, vegetable oils and meals, meat and dairy. However, the list excludes US soya beans, which will continue to face an additional 10% duty (LSEG).

In fundamental news:

  • French maize crop ratings stabilised week-on-week as of September 21. However, only 23% of crops were rated good or excellent, compared with 62% a year earlier. French maize harvest progress accelerated to 45% complete. This is up from 27% the previous week and well ahead of the 13% recorded at the same point last year (FranceAgriMer)
  • The latest USDA Crop Progress report, covering the week ending September 20, showed the US maize harvest at 13% complete. This was up from 8% the previous week and slightly ahead of the five-year average of 11%. The next update will be out this evening. But looking ahead, some rains are forecast over the US Midwest, which could slow harvest progress

Table 1. Global grain futures prices

Futures market UK feed wheat Paris milling wheat Chicago wheat Chicago maize
Contract month Nov-26 Dec-26 Dec-26 Dec-26
Price (per tonne) £205.75 €236.75 $258.37 $207.97
Change on week -£4.00 -€4.75 -$4.04 +$0.30

UK delivered cereal prices

Delivered feed wheat into Yorkshire, Oct-26, was quoted at £219.50/t last Thursday, with no comparison on the week.

Delivered into the same location in Nov-26 was quoted at £220.50/t, with no comparison week-on-week. This equated to a £13.00/t premium to UK feed wheat futures (Nov-26).

Delivered feed wheat into the West Midlands, Nov-26, was quoted at £217.50/t, at a £10.00/t premium to UK feed wheat futures (Nov-26).

Table 2. UK delivered cereal prices

Delivery specification N'hants bread wheat E. Anglia feed wheat Yorkshire feed wheat E. Anglia feed barley
Delivery month Nov-26 Nov-26 Nov-26 Nov-26
Price (per tonne) n/a n/a £220.50 n/a
Change on week n/a n/a n/c n/a

n/a = not available

n/c = no comparison available.

Rapeseed

Paris rapeseed futures in £/t (Nov-26)

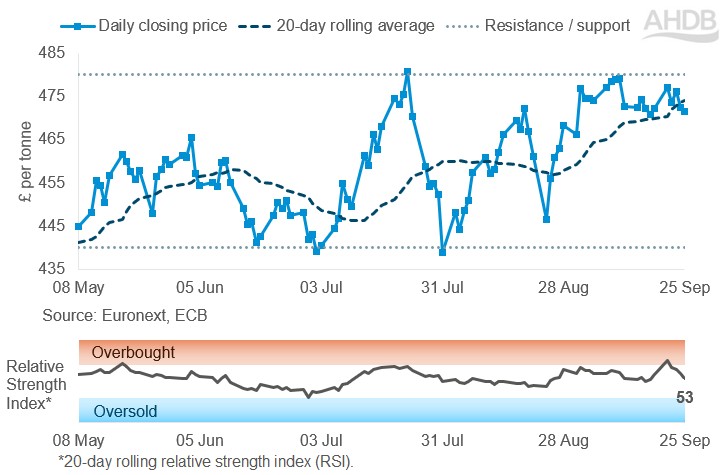
Figure 2. Paris rapeseed futures prices, Nov-26 contract (£/tonne)

A graph showing Paris rapeseed futures prices in pound sterling


Nov-26 Paris rapeseed futures prices fluctuated last week but ended Friday little changed. In £/t the Nov-26 contract ended Friday at approx. £471.50/t, 0.1% below the price on Friday 18 September (Figure 2).

The contract also slipped below the 20-day rolling average towards the end of last week.

In Figure 2, the solid line with markers shows the Nov-26 contract prices and the dashed line shows the 20-day rolling average.

If the Nov-26 prices stay below the 20-day rolling average this week, it could bring more pressure on prices. This suggests that it could be worth paying more attention to the market this week.

The Relative Strength Index (RSI) also fluctuated over the week. The RSI ended Friday at 53, down from 58 on 18 September.

Market drivers

Oilseed futures prices continued to trade in wider ranges last week but ended the week with relatively small changes. Fluctuations in crude oil prices and exchange rates, plus mixed crop news, influenced prices through the week.

Nearby Brent crude oil futures prices traded in an almost $11/barrel range last week.

Prices fell, rose, and fell again during the week on news about the conflict in the Middle East. The contract closed at $104.32/barrel on Friday, up 0.4% from 18 September.

Nov-26 Paris rapeseed futures fell 0.3% last week. However, Nov-26 Chicago soya bean futures rose 1.2%, while Nov-26 Winnipeg canola futures gained 0.8%.

The market awaited the outcome of the US-China talks as delays in harvesting US soya beans supported spot US soya bean prices.

Reports of below-average canola yields in Canada so far, and a weaker Canadian dollar supported Winnipeg prices.

This morning, the USA and China announced that China will reduce import tariffs for many US agricultural products. But US soya beans will still face a 10% tariff into China, which could be seen as negative for US soya bean export demand.

The USDA will release the USA's quarterly estimate of soya bean stocks on Wednesday and give more insight to total demand.

Coceral trimmed its 2026 EU rapeseed crop estimate by 0.2 Mt to 20.0 Mt last week, now 0.5 Mt below last year’s crop. But the cut was more than offset by increases to sunflower seed output.

Rapeseed prices for harvest 2027 found a little more support last week. Nov-27 Paris rapeseed futures rose 0.2% last week and Nov-27 Winnipeg canola gained 1.6%.

After a hot, dry September, private analysts Expana suggested the French rapeseed area could fall by 10-15%. Largely as a result, the company forecasts the EU-27 2027 area to fall by 2%.

Table 3. Global oilseed and oil futures prices

Futures market Paris rapeseed Chicago soya beans Chicago soya bean oil Brent crude oil
Contract month Nov-26 Nov-26 Dec-26 nearby
Price (per tonne) €548.00 $484.60 $1,495.60 $104.32
Change on week -€1.75 +$5.69 -$8.38 +$0.45

*Brent crude oil price per barrel

UK delivered rapeseed prices

The direction of delivered Erith prices for rapeseed varied for different months last week.

The delivered price for October delivery declined by £3.00/t from the previous week to £474.50/t, while the price for November was unchanged at £479.50/t.

In contrast, the prices for February and May 2027 rose slightly, up £1.00/t and £1.50/t respectively.

The delivered prices for Liverpool followed a similar pattern to those for Erith.

Table 4. UK delivered rapeseed prices

Delivery specification Erith Liverpool East Anglia
Delivery month Nov-26 Nov-26 Nov-26
Price (per tonne) £479.50 £479.00 n/a
Change on week unch unch n/a

n/a = not available

n/c = no comparison available.

Extra information

Last week, we published the end of season estimates for UK cereal supply and demand in the 2025/26 season.

The estimates show residuals for wheat and maize, after the full season official statistics have been considered. This article looks at why there might be a residual for wheat in 2025/26.

Our final harvest progress report of 2026 showed yields remain disappointing as harvest nears completion. On the farms surveyed, there was still a small area of spring barley left to be cut, as well as some pulses in Northern Ireland. Anecdotally, there are also some spring oats and spring barley remaining in the north of Scotland.

This Thursday, 1 October 2026, we will release data on cereals used to produce GB compound feed and used by the human and industrial sectors in August.


Sign up to receive the latest information from AHDB

While AHDB seeks to ensure that the information contained on this webpage is accurate at the time of publication, no warranty is given in respect of the information and data provided. You are responsible for how you use the information. To the maximum extent permitted by law, AHDB accepts no liability for loss, damage or injury howsoever caused or suffered (including that caused by negligence) directly or indirectly in relation to the information or data provided in this publication.

All intellectual property rights in the information and data on this webpage belong to or are licensed by AHDB. You are authorised to use such information for your internal business purposes only and you must not provide this information to any other third parties, including further publication of the information, or for commercial gain in any way whatsoever without the prior written permission of AHDB for each third party disclosure, publication or commercial arrangement. For more information, please see our Terms of Use and Privacy Notice or contact the Director of Corporate Affairs at info@ahdb.org.uk  © Agriculture and Horticulture Development Board. All rights reserved. 

×