Arable Market Report – 14 September 2026

Monday, 14 September 2026

This week's view of grain and oilseed markets, including a summary of both UK and global activity.

Grains

UK feed wheat futures (Nov-26)

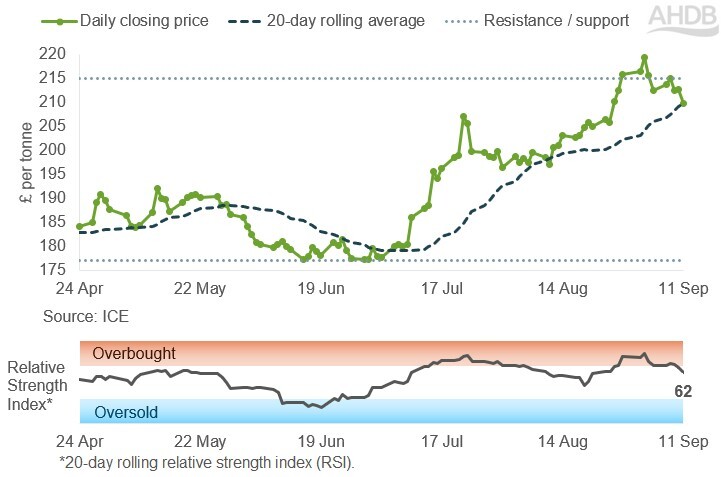
Figure 1. UK feed wheat futures prices, Nov-26 contract (£/tonne)

Nov-26 UK feed wheat futures closed at £209.75/t on Friday, down £2.75/t or 1.3% from the previous week.

The contract held above £212/t for most of the week but moved lower on Friday.

The Nov-26 contract’s prices are shown by the green line with markers in Figure 1.

Friday’s price was still just above the 20-day rolling average, shown by the dashed line in Figure 1.

This rolling average may act as a support line, but this will depend on the momentum in the world market.

A support line is a level that prices may find it harder to move below.

The Relative Strength Index (RSI) declined from 70 on 4 September to 62 on 11 September.

Find out more about the graphs in this report and how to use them

Market drivers

Global grain markets ended last week lower after the USDA released its latest monthly report on Friday.

Dec-26 Paris wheat futures lost 2.1% over the week. Both Dec-26 Chicago wheat futures and Dec-26 Chicago maize futures fell 1.2%

Ahead of the report, speculative traders had bought heavily into the futures markets. But after the report, prices turned lower and contracts were sold to book profits from the earlier buys.

The USDA cut its forecast of the US 2026 maize crop by 5.4 Mt to 401.3 Mt due to the impact of hot weather this summer on yields.

But the resulting fall in 2026/27 US maize stocks was less than the market had expected.

An unexpected increase in the forecast of global wheat stocks at the end of 2026/27 from August also led to prices declining.

Global wheat stocks at the end of this season are now forecast at 276.3 Mt, up 3.0 Mt from August’s report. This is largely due to increased crop estimates for Australia and Canada.

Earlier in the week, hopes that talks between Russia and Ukraine might be possible weighed on prices. However, further air strikes on key infrastructure and data showing the ongoing disruption to Black Sea trade limited the price impact.

SovEcon cut its forecast of Russian wheat exports in 2026/27 by 3.2 Mt to 41.4 Mt due to the conflict. The USDA estimates that Russia shipped 48.0 Mt of wheat last season.

The EU is shipping more barley to Middle Eastern countries due to the conflict in the Black Sea. Between 1 July and 7 September, the EU had shipped 887 Kt of barley to Saudi Arabia, compared to 411 Kt in the same period last season (EU Commission).

Final data confirmed high quality for French wheat this year. FranceAgriMer reports that over 50% of the 2026 crop met the requirements for ‘premium grade’, compared to the five-year average of 15%.

Table 1. Global grain futures prices

Futures marketUK feed wheatParis milling wheatChicago wheatChicago maize
Contract month Nov-26 Dec-26 Dec-26 Dec-26
Price (per tonne) £209.75 €241.00 $266.46 $208.76
Change on week -£2.75 -€5.25 -$3.21 -$2.56

UK delivered cereal prices

The price for feed wheat to be delivered into East Anglia in November (2026) was £215.50/t in last week’s survey.

No direct week-on-week comparison is available, but the price is unchanged from that reported two weeks ago. The price is also £47.50/t higher than that for feed wheat delivered in East Anglia in Nov-25 a year ago.

Bread wheat to be delivered into Northamptonshire in November was £228.50/t. This equated to a £16.00/t premium to the Nov-26 UK feed wheat futures price on the same day.

While the total price is higher than the equivalent price a year ago, the premium to the futures price is lower. A year ago, the price for November 2025 delivery into Northamptonshire was £24.00/t above the Nov-25 UK feed wheat futures price on the same day.

Table 2. UK delivered cereal prices

Delivery specificationN'hants bread wheatE. Anglia feed wheatYorkshire feed wheatE. Anglia feed barley
Delivery month Nov-26 Nov-26 Nov-26 Nov-26
Price (per tonne) £228.50 £215.50 n/a n/a
Change on week n/c n/c n/a n/a

n/a = not available

n/c = no comparison available.

Rapeseed

Paris rapeseed futures in £/t (Nov-26)

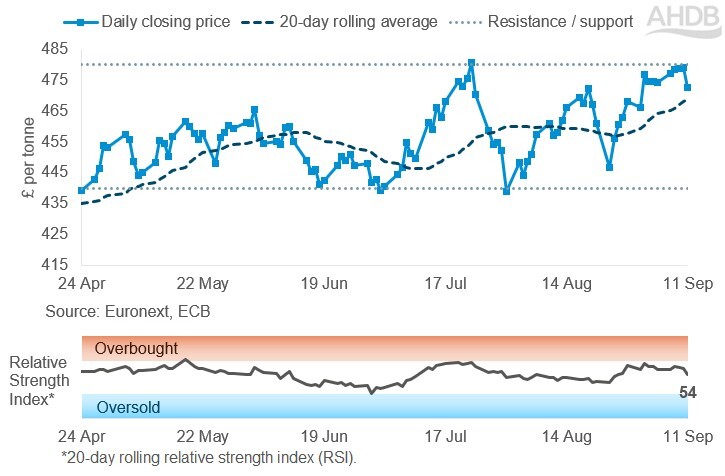
Figure 2. Paris rapeseed futures prices, Nov-26 contract (£/tonne)

Nov-26 Paris rapeseed futures lost 0.3% last week in £/t and ended Friday’s trading at approx. £472.60/t.

The Nov-26 contract’s prices are shown by the solid line with markers in Figure 2.

The contract rose through most of the week but lost approx. £6.50/t on Friday.

The contract remains above the 20-day rolling average, shown by the dashed line in Figure 2. This rolling average may act as a support line, but this will depend on the momentum in the world market.

A support line is a level that prices may find it harder to move below.

The Relative Strength Index (RSI) declined from 59 on 4 September to 54 on 11 September.

Find out more about the graphs in this report and how to use them

Market drivers

Oilseed futures prices came under pressure on Friday after a surprise increase to the US soyabean crop estimate.

Prices were underpinned by the ongoing conflicts in the Middle East and the Black Sea for most of the week.

Nearby Brent crude oil futures pushed above $100/barrel for the first time since May due to the Middle East conflict. The contract ended Friday at $104.61/barrel, up 8.7% Friday-Friday.

Another factor was China continuing to buy US soyabeans. Reuters estimates that China bought a further 1.0 Mt last week.

However, on Friday, the USDA made a surprise increase to its US soyabean crop estimate and cut US stocks by less than expected.

This triggered selling and profit-taking by speculative traders, which in turn added to the price declines.

Nov-26 Chicago soyabean futures fell 1.0% over the week.

Nov-26 Paris rapeseed futures fell 0.2% Friday-Friday, while Nov-26 Winnipeg canola futures lost 0.6%.

The USDA increased its estimate of the US 2026 soyabean crop by 0.4 Mt to 123.4 Mt, now 7.4 Mt more than last season. However, the market had expected a small decrease in the crop due to the mixed weather conditions over the past month.

The Canadian canola harvest remains slow due to previous wet weather posing risks to the quality of the harvest. The forecast looks drier for this week, which could help progress.

Crude oil is likely to remain a key driver this week. There have been strikes against Saudi Arabia’s East-West pipeline over the weekend. The pipeline is more important with traffic remaining slower through the Strait of Hormuz.

Table 3. Global oilseed and oil futures prices

Futures marketParis rapeseedChicago soyabeansChicago soyabean oilBrent crude oil
Contract month Nov-26 Nov-26 Dec-26 nearby
Price (per tonne) €550.75 $476.33 $1,536.17 $104.61
Change on week -€1.25 -$4.87 +$9.04 +$8.33

*Brent crude oil price per barrel

UK delivered rapeseed prices

The delivered price for rapeseed into Erith in Nov-26 was £482.50/t according to our survey on Friday. This was unchanged from the previous week. 

The Erith delivered price for harvest-27 was also unchanged week-on-week at £452.50/t.

This survey is carried out on a Friday morning, so the changes may not fully reflect the closing prices for the Paris futures market.

Table 4. UK delivered rapeseed prices

Delivery specificationErithLiverpoolEast Anglia
Delivery month Nov-26 Nov-26 Nov-26
Price (per tonne) £482.50 £482.50 £481.50
Change on week unch unch +£0.50

Extra information

On Friday, AHDB published data on imports and exports in July 2026 from HMRC.

In the first month of the 2026/27 marketing season, the UK imported 195 Kt of wheat. This is 23% less than the first month of the 2025/26 season.

However, the UK also imported 215 Kt of maize in July, a sharp rise from the 136 Kt in the same month last season.

Meanwhile, in July the UK exported 29 Kt of barley, just 11 Kt of wheat and 9 Kt of oats. 

Get the full data on AHDB’s trade data webpage.

UK natural gas futures prices continued to push higher last week due to the conflict in the Middle East. The nearby contract gained 11% Friday-Friday and ended the week over 198 pence per therm.

This poses a risk to the cost of producing nitrogen fertilisers.

In the week ending 4 September in GB, the price for imported AN (34.5% N) averaged £466/t, up £4/t from the previous week. The price for UK produced AN was unchanged week-on-week at £461/t.

Northern Ireland

Table 5. Delivered prices into Belfast*

Delivery specification**Feed barley  - spotFeed barley  - forwardFeed wheat  - spotFeed wheat  - forward
Delivery month Spot Nov-26 Spot Nov-26
Price (per tonne) £218.50 £223.50 £235.50 £237.50
Change on week n/c n/c -£2.50 -£2.50

*Prices provided for indicative purposes

**Basis is imported/home-grown

n/c = no comparison available


Sign up to receive the latest information from AHDB

While AHDB seeks to ensure that the information contained on this webpage is accurate at the time of publication, no warranty is given in respect of the information and data provided. You are responsible for how you use the information. To the maximum extent permitted by law, AHDB accepts no liability for loss, damage or injury howsoever caused or suffered (including that caused by negligence) directly or indirectly in relation to the information or data provided in this publication.

All intellectual property rights in the information and data on this webpage belong to or are licensed by AHDB. You are authorised to use such information for your internal business purposes only and you must not provide this information to any other third parties, including further publication of the information, or for commercial gain in any way whatsoever without the prior written permission of AHDB for each third party disclosure, publication or commercial arrangement. For more information, please see our Terms of Use and Privacy Notice or contact the Director of Corporate Affairs at info@ahdb.org.uk  © Agriculture and Horticulture Development Board. All rights reserved. 

×