Arable Market Report – 21 September 2026

Monday, 21 September 2026

This week's view of grain and oilseed markets, including a summary of both UK and global activity.

Grains

UK feed wheat futures (Nov-26)

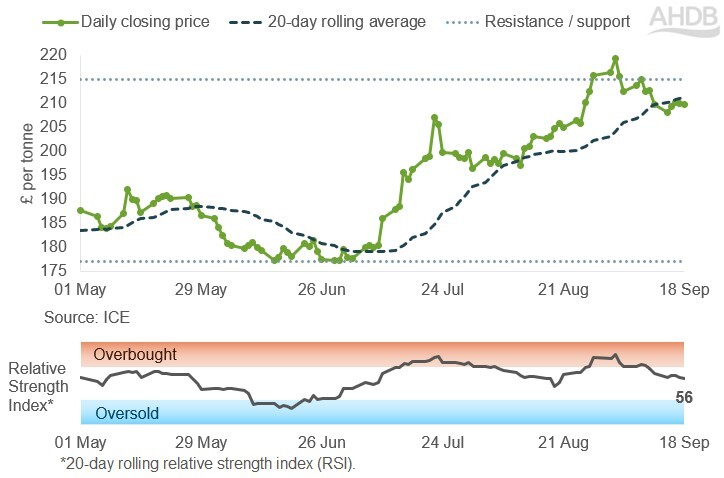
Figure 1. UK feed wheat futures prices, Nov-26 contract (£/tonne)

Nov-26 UK feed wheat futures closed at £209.75/t on Friday, unchanged from the previous week.

The contract dropped at the start of the week and then recovered but dropped again on Friday to settle unchanged.

In Figure 1, the solid line with markers shows the contract’s prices.

The Relative Strength Index (RSI) declined from 62 on 11 September to 56 on 18 September.

Find out more about the graphs in this report and how to use them

Market drivers

Global grain markets were mixed last week, with Black Sea developments and US harvest weather driving sentiment.

Hopes of improved Black Sea export flows weighed on prices. But concerns over the French maize crop and uncertainty around US harvest progress offered support.

As a result, nearby US wheat and maize futures fell by 1.5% and 0.5% respectively week-on-week. Meanwhile, nearby Paris milling wheat prices gained 0.2%.

Black Sea developments were a key source of volatility for grain markets. Traders balanced continued Russian and Ukrainian attacks against hopes that a Turkish-backed truce on commercial shipping could reduce disruption and improve export flows.

Ongoing Russian and Ukrainian wheat shipments, including sizeable offers from Baltic ports, limited the market’s reaction to buying interest from Algeria and Pakistan.

Meanwhile, the prospect of de-escalation encouraged speculative selling and reduced fund exposure. Black Sea shipping and export flows remain a critical watch point for grain prices.

French maize conditions deteriorated further last week, with just 23% of the crop rated good or excellent by 14 September. This is another record low, and sharply below the 62% a year earlier.

However, the impact of the heat and drought is already well established. The projected 42% year-on-year production decline is largely priced into the market.  So, the latest data generated limited price upside.

Harvesting has also accelerated significantly, reaching 27% complete, versus a five-year average of 5%. This reinforced the focus on yields and physical availability.

A focus of the market right now is US maize harvest progress. The weather in the US Midwest is expected to remain unsettled over the coming week.

The US maize harvest was 8% complete as of 13 September, slightly ahead of both last year and the five-year average. A further update is expected this evening.

President Donald Trump and Chinese President Xi Jinping are due to meet in Washington on 24 September. Agriculture and tariffs are expected to feature prominently in discussions.

Any progress towards lower Chinese tariffs or commitments to buy US agricultural goods, particularly soybeans, would be supportive for US oilseeds. It could also improve the sentiment in the grain complex, including maize and wheat.

However, expectations remain cautious. Without clear commitments, the meeting could generate limited or short-lived market support.

Table 1. Global grain futures prices

Futures marketUK feed wheatParis milling wheatChicago wheatChicago maize
Contract month Nov-26 Dec-26 Dec-26 Dec-26
Price (per tonne) £209.75 €241.50 $262.42 $207.68
Change on week unch +€0.50 -$4.04 -$1.08

UK delivered cereal prices

The price for feed wheat to be delivered into East Anglia in November 2026 was £212.50/t in last week’s survey, down £3.00/t across the week.

Delivered feed wheat into Avonmouth was quoted at £220.50/t for the same period.

Bread wheat to be delivered into the North West in November was £237.00/t. This equated to a £27.00/t premium to the Nov-26 UK feed wheat futures price on the same day.

Bread wheat into Yorkshire was quoted at £232.00/t, a £22.00/t premium to Nov-26 futures.

Table 2. UK delivered cereal prices

Delivery specificationN'hants bread wheatE. Anglia feed wheatYorkshire feed wheatE. Anglia feed barley
Delivery month Nov-26 Nov-26 Nov-26 Nov-26
Price (per tonne) £225.50 £212.50 n/a n/a
Change on week -£3.00 -£3.00 n/a n/a

n/a = not available

n/c = no comparison available.

Rapeseed

Paris rapeseed futures in £/t (Nov-26)

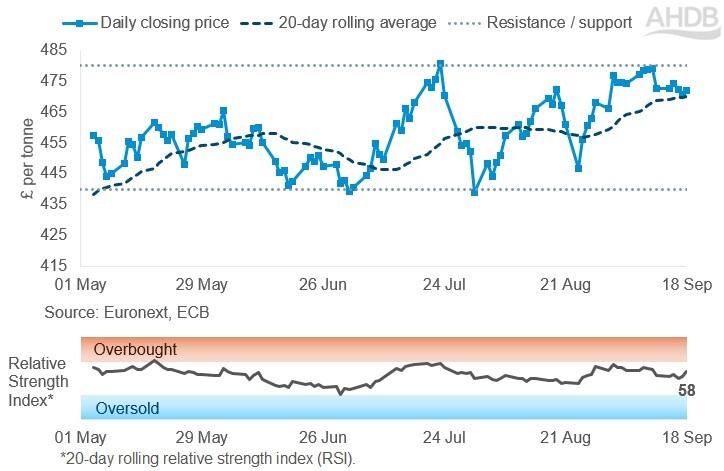
Figure 2. Paris rapeseed futures prices, Nov-26 contract (£/tonne)

Nov-26 Paris rapeseed futures ended last week at a little over £472/t on Friday. This was a small decrease of 0.1% from the previous Friday.

The contract prices remained above the 20-day rolling average, which seems to the acting as a support line.

A support line is a level that prices can find it harder to move below.

In Figure 1, the solid line with markers shows the Nov-26 prices, while the dashed line shows the 20-day rolling average.

Friday-Friday, the Relative Strength Index (RSI) increased from 54 to 58.

Find out more about the graphs in this report and how to use them

Market drivers

It was another volatile week for oilseed markets, but with small Friday-Friday changes. The conflicts in the Middle East and Black Sea, and profit-taking by speculative traders, had the most impact on prices.

Strikes against a key Saudi Arabian oil pipeline pushed crude prices up in the early part of the week. Nearby Brent crude oil futures reached $108.75/barrel on Tuesday.

There were also further attacks on energy infrastructure in Ukraine and Russia.

But hopes around Saudi exports and profit-taking pushed prices lower later in the week. The nearby Brent crude oil futures ended Friday at $103.87/barrel, down 0.7% from a week earlier.

Nov-26 Paris rapeseed futures lost 0.2% over the week, but the Aug-27 futures price gained 1.1%.

In contrast, Nov-26 Winnipeg canola futures gained 0.6% over the week due to a weaker Canadian dollar and wet weather during the harvest in Canada.

In Canada’s top canola-producing province, Saskatchewan, just 15% has been harvested by mid-September. This is the slowest pace since 2019.

Statistics Canada forecast the canola crop at 22.1 Mt last week, just 0.8% lower than last year’s record.

But the wet weather means ongoing doubts about the crop’s quality and is offsetting pressure from the crop projection for now.

Meanwhile, Nov-26 Chicago soya bean futures gained 0.5% last week. Stronger soyameal prices and hopes for Chinese demand helped the Chicago market.

This week, the conflicts in the Middle East and Black Sea, plus the Chinese state visit to the USA will be in focus. The market expects agricultural trade will be discussed during the visit.

Looking further ahead, planting of the 2026/27 South American soya bean crops will be watched closely. Planting is in the opening stages in Brazil.

Table 3. Global oilseed and oil futures prices

Futures marketParis rapeseedChicago soya beansChicago soya bean oilBrent crude oil
Contract month Nov-26 Nov-26 Dec-26 nearby
Price (per tonne) €549.75 $478.91 $1,503.98 $103.87
Change on week -€1.00 +$2.57 -$32.19 -$0.74

*Brent crude oil price per barrel

UK delivered rapeseed prices

The Erith delivered price for rapeseed in November was £479.50/t in Friday’s survey. This was £3.00/t lower than the previous week and echoed the trend in the Nov-26 futures prices.

The price for May-27 declined by £3.50/t over the same period to £486.00/t.

However, the price for harvest-27 gained £2.00/t to £454.50/t.

Table 4. UK delivered rapeseed prices

Delivery specificationErithLiverpoolEast Anglia
Delivery month Nov-26 Nov-26 Nov-26
Price (per tonne) £479.50 £479.00 £478.50
Change on week -£3.00 -£3.50 -£3.00

Extra information

Following the sharp price increases seen during the spring, fertiliser markets were more stable through May and June. However, prices became more volatile during July and August, with periods of both price increases and reductions across key nitrogen products. Read more information in the Fertiliser markets: Summer update.

Tomorrow, AHDB will release the end-of-season supply and demand estimates for the 2025/26 marketing year. All information will be published on UK cereals supply and demand estimates page.

This Friday, 28 September, AHDB will release the final harvest report for the 2026 harvest campaign. The latest information will be on the Harvest progress in the UK page of the AHDB website, and give further information on yields and quality.

Northern Ireland

Due to insufficient quotes, we are unable to publish delivered Belfast cereals prices for 18 September 2026.


Sign up to receive the latest information from AHDB

While AHDB seeks to ensure that the information contained on this webpage is accurate at the time of publication, no warranty is given in respect of the information and data provided. You are responsible for how you use the information. To the maximum extent permitted by law, AHDB accepts no liability for loss, damage or injury howsoever caused or suffered (including that caused by negligence) directly or indirectly in relation to the information or data provided in this publication.

All intellectual property rights in the information and data on this webpage belong to or are licensed by AHDB. You are authorised to use such information for your internal business purposes only and you must not provide this information to any other third parties, including further publication of the information, or for commercial gain in any way whatsoever without the prior written permission of AHDB for each third party disclosure, publication or commercial arrangement. For more information, please see our Terms of Use and Privacy Notice or contact the Director of Corporate Affairs at info@ahdb.org.uk  © Agriculture and Horticulture Development Board. All rights reserved. 

×