Arable Market Report – 02 November 2026

Monday, 2 November 2026

This week's view of grain and oilseed markets, including a summary of both UK and global activity.

Grains

UK feed wheat futures May-2027

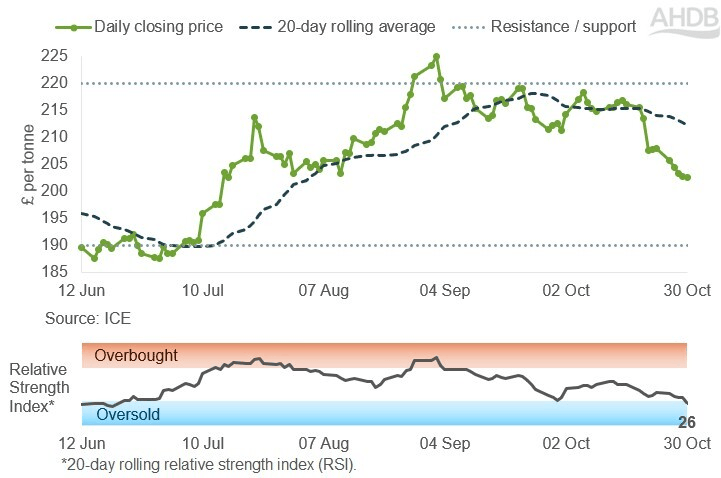
Figure 1. UK feed wheat futures prices, Nov-2026 contract, in £/tonne

UK feed wheat future price 2 11 2026

May-2027 UK feed wheat futures fell by £5.50/t or 2.6% last week to £202.50/t.

The solid line with markers in Figure 1 shows the May-2027 prices.

Prices seemed to steady at the end of the week, echoing the trend in May-2027 Paris wheat futures. Both contracts are close to important psychological levels: £200/t for UK futures and €225/t for Paris futures.

The Relative Strength Index (RSI) for the UK feed wheat futures contract was 26 on Friday. This is down from 40 a week earlier and now in the oversold zone, which may lead to a change in the price trend.

However, market news will determine if prices find support or face further pressure.

Meanwhile, the Nov-2026 UK feed wheat futures contract fell £1.00/t or £0.5% last week to £192.75/t. The Nov-2026 contract’s trading day is 23 November, and in its final weeks, a contract can become less reflective of physical prices. So, this report focuses on the May-2027 prices.

Find out more about the graphs in this report and how to use them

Market drivers

Grain prices fell last week on hopes for an increase in Russian exports, US maize harvest progress and selling by speculative traders.

However, price declines paused later in the week. This followed attacks on shipping in the Black Sea, higher crude oil prices and signs of stronger international demand.

May-2027 Paris wheat futures fell 2.3%, with Chicago wheat futures down 3.1% and Chicago maize down 2.1%.

While they remain below recent years, Russian grain exports have increased through the Baltic ports recently. The previous week’s talks also increased optimism for Black Sea shipments.

Reuters reports Russia approved vessels to leave the Sea of Azov into the Black Sea for the first time since 10 July. Russia is also starting some exports from the Arctic port of Murmansk.

Meanwhile, Jordan, Tunisia and South Korea all bought grain or issued tenders last week. US weekly net export sales for wheat also came in at 850 Kt, above expectations of 200-500 Kt.

The US maize harvest reached 70% complete by 25 October. The USDA also reported over three-quarters of the 2027 winter wheat area sown.

Meanwhile, the EU Commission cut its estimate of the bloc’s maize crop by another 1.3 Mt to 47.0 Mt due to the drought. The MARS report also showed mixed conditions for planting winter wheat and barley in the EU.

Short-term market attention is likely to remain on geopolitical factors. This will include how Russian grain ships fare in the Black Sea and tomorrow’s US mid-term elections. Any changes to the strength of the US dollar will impact grain and oilseed prices globally.

Meanwhile, wheat harvesting is progressing in Australia and now underway in Argentina. The Buenos Aires Grain Exchange reports positive early wheat yields in Argentina, and that maize planting is going well.

Table 1. Global grain futures prices

Futures market Contract month Price per tonne Change on week
UK feed wheat May-2027 £202.50 −£5.50
Paris milling wheat May-2027 €228.50 −€5.25
Chicago wheat May-2027 $229.17 −$7.26
Chicago maize May-2027 $184.65 −$3.94

n/a = not available
n/c = no comparison available

Futures prices are indicative, and not representative of physical trading values. The latest daily futures settlement prices are available on our website. You can view the full data series here and download your own customised report by selecting the commodity, timescale and currency. If you need any help please contact cereals.mi@ahdb.org.uk

UK delivered cereal prices

The November delivered price for bread wheat in Yorkshire was £217.00/t as of Thursday 29 October, with December delivery at £218.50/t. No week-on-week comparison is available.


The November price equated to a £24.00/t premium over the Nov-2026 UK feed wheat futures price on the same day. The May delivered price, of £226.50/t, also equated to a £24.00/t premium over the May-2027 UK feed wheat futures price.


Meanwhile, the delivered price for bread wheat in Northamptonshire in May was £220.00/t. This equated to a £17.50.00/t premium over the May-2027 UK feed wheat futures price.

Table 2. UK delivered wheat prices

Delivery specification Delivery month Price per tonne Change on week
N'hants bread wheat May-2027 £220.00 n/c
E. Anglia feed wheat May-2027 n/a n/a
Yorkshire feed wheat May-2027 n/a n/a
E. Anglia feed barley May-2027 n/a n/a

n/a = not available
n/c = no comparison available

Rapeseed

Paris rapeseed futures in £/t, May-27

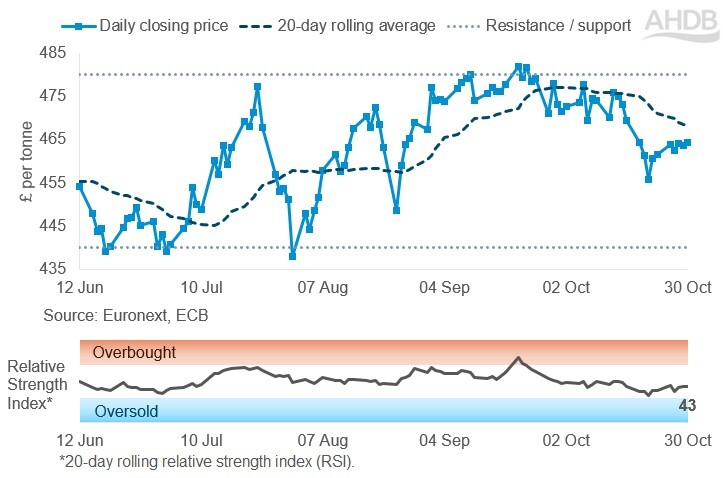
Figure 2. Paris rapeseed futures prices, Nov-26 contract, in £/tonne

OSR Paris future price 2 11 2026


May-2027 Paris rapeseed futures gained 0.6% in £/t last week to approx. £464/t.

The weekly fall was larger in £/t than in euro terms because of sterling strengthening against the euro.

The pound strengthened from € 1.1943 on 23 October to € 1.1993 on 30 October.

The May-2027 contract is still below the 20-day and 50-day rolling averages but has surpassed the 5-day rolling average.

Market momentum is limited as prices have drifted and remain within recent ranges. The Relative Strength Index (RSI) was at 43 on Friday, up from 39 last week, moving away from oversold.

Find out more about the graphs in this report and how to use them

Market drivers

Oilseed market continues to remain volatile but broadly pressured across the week, with rapeseed the only major oilseed escaping the weekly pressure. Sustained high crude oil prices, currency and US harvest progress were the main drivers across the week.

Over the last week, May-2027 Paris rapeseed futures gained 0.6%. May-2027 Winnipeg canola futures fell 1.2% and May-2027 Chicago soyabeans dropped 2.4%.

Sterling strengthened against the euro through the week to 30 October, and has strengthened by 2.5% since 30 September.

The US soyabean harvest is now well advanced, which is likely to have added to the continued pressure across the week. According to the latest USDA crop progress report, as of 25 October, the US soyabean harvest was 79% complete, up from 64% the previous week. This was in line with trade expectations and slightly ahead of the five-year average of 77%.

With a mildly wet US Midwest last week, some progress for the soyabean crop could have been slightly delayed. This could continue into this week, with the next seven days forecast remaining mildly wet for the Midwest. This could dampen the harvest progress, but shouldn’t impact market sentiment, as a record US soyabean crop comes to market.

Looking forward, the drought-hit sowing in France likely caused Expana's sharper cut to its 2027/28 EU rapeseed area forecast, which may have supported Paris rapeseed relative to the wider oilseed market. Plantings are now expected to fall 5% year on year to 6.1 million hectares, compared with the 2% drop forecast last month. In contrast, the sunflower area forecast was unchanged, and soyabean area was raised by 2%, leaving rapeseed as the only oilseed with a tighter supply outlook for next season.

Malaysia's finance ministry is reviewing a proposal to temporarily suspend crude palm oil export taxes for three to five months. The proposal follows a rise in national stocks to a record 3.5 Mt in September. A suspension would aim to support export demand and reduce inventories, which could increase the supply of more competitively priced palm oil on the global market. While a decision is pending, any further pressure on palm oil prices remains a key watchpoint.

January-2027 Brent crude futures traded broadly sideways for most of last week, then rose 2.4% on Friday to close at $113.43/barrel. The rise was driven by continued Middle East tensions. This morning, January 2027 Brent fell around 3% on US-Iran peace talks. Higher Brent crude prices likely still adding price support to the oilseed market.

Table 3. Global oilseed and oil futures prices

Futures market Contract month Price per tonne Change on week
Paris rapeseed May-2027 €557.00 +€5.75
Chicago soyabeans May-2027 $460.54 −$11.21
Chicago soyabean oil May-2027 $1,477.30 −$13.23
Brent crude oil* nearby $113.43 +$1.73

*Brent crude oil price per barrel
n/a = not available
n/c = no comparison available

Futures prices are indicative, and not representative of physical trading values. The latest daily futures settlement prices are available on our website. You can view the full data series here and download your own customised report by selecting the commodity, timescale and currency. If you need any help please contact cereals.mi@ahdb.org.uk

UK delivered rapeseed prices

The delivered price for rapeseed into Erith in November was £465.50/t in Friday’s survey, up £3.00/t from last week. The delivered price for Liverpool in November was also £465.50/t, up £2.00/t on the week.

The delivered price into East Anglia in November was £464.00/t, with no comparison on the week.

Erith and Liverpool prices for February delivery gained £1.00/t and £0.50/t respectively, both landing at £470.50/t. East Anglia prices for February also saw upward price pressure, gaining £1.00/t to £469.00/t.

The delivered price for harvest 2027 was down £0.50/t on the week to £448.50/t for both Erith and Liverpool.

Table 4. UK delivered rapeseed prices

Delivery specification Delivery month Price per tonne Change on week
Erith May-2027 £474.00 +£0.50
Liverpool May-2027 £474.00 +£0.50
East Anglia May-2027 £472.50 +£1.00

n/a = not available
n/c = no comparison available

Extra information

The AHDB Cereal Quality Survey for the 2026 harvest is scheduled for release tomorrow (3 November). This will provide insight into the quality of this season's wheat and barley crops.


AHDB is also due to publish updates on UK human and industrial cereal usage and GB animal feed production in September this Thursday (5 November). The data will offer further insight into early-season domestic cereal demand.

Northern Ireland

Table 5. Delivered prices into Belfast*

Delivery specification** Feed barley  - spot Feed barley  - forward Feed wheat  - spot Feed wheat  - forward
Delivery month Spot Feb-2027 Spot Feb-2027
Price (per tonne) n/a n/a n/a n/a
Change on week n/a n/a n/a n/a

*Prices provided for indicative purposes.
**Basis is imported/home-grown.
n/c: no comparison
unch: no change in price compared to last week


Sign up to receive the latest information from AHDB

While AHDB seeks to ensure that the information contained on this webpage is accurate at the time of publication, no warranty is given in respect of the information and data provided. You are responsible for how you use the information. To the maximum extent permitted by law, AHDB accepts no liability for loss, damage or injury howsoever caused or suffered (including that caused by negligence) directly or indirectly in relation to the information or data provided in this publication.

All intellectual property rights in the information and data on this webpage belong to or are licensed by AHDB. You are authorised to use such information for your internal business purposes only and you must not provide this information to any other third parties, including further publication of the information, or for commercial gain in any way whatsoever without the prior written permission of AHDB for each third party disclosure, publication or commercial arrangement. For more information, please see our Terms of Use and Privacy Notice or contact the Director of Corporate Affairs at info@ahdb.org.uk  © Agriculture and Horticulture Development Board. All rights reserved. 

×