Arable Market Report – 26 October 2026

Monday, 26 October 2026

This week's view of grain and oilseed markets, including a summary of both UK and global activity.

Grains

UK feed wheat futures, Nov-2026

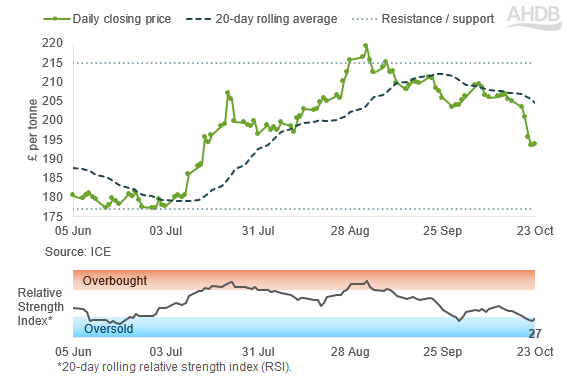
Figure 1. UK feed wheat futures prices, Nov-2026 contract, in £/tonne

UK feed wheat futures were down last week, following pressure in the global market. The Nov-2026 contract closed at £193.75/t, losing £11.25/t week-on-week.

The Nov-26 contract prices are shown by the solid line with markers in Figure 1.

Prices have remained below the 20-day moving average, and momentum indicators have weakened again. This suggests near-term downside pressure, as the market has now entered oversold territory.

The Relative Strength Index (RSI) was at 27 on Friday.

Find out more about the graphs in this report and how to use them

Market drivers

Global grain markets fell across the week. Markets were pressured by improving global supply prospects and US harvest progress, outweighing support from continued Black Sea disruption and firm crude oil prices. However, hopes of Russia–Ukraine peace talks developing also weighed on prices.

Nearby Chicago wheat futures were down 6.5%, while Chicago maize fell 3.9%, and Paris milling wheat futures dropped 4.0%. 

The market continues to unwind the US weather risk premium as dry conditions across key producing states, including Nebraska, Kansas and Oklahoma, have supported field work over the past week, allowing winter wheat planting. 

Further to that, broadly favourable weather across the US Midwest has aided the progression of the maize harvest, guaranteeing supplies of some of the 2026 crop. The market is pressured in anticipation of this large crop coming to market.

The latest USDA crop progress report out this evening (20:00 GMT) is expected to reflect this progress.

Looking ahead, forecasts point to dry conditions across the USA over the next three days and only light rainfall over the coming week, so harvest and planting look set to progress well into next week. This could continue to add downward pressure on prices.

In other supply news, the Rosario Stock Exchange has raised its estimate for Argentina's 2026/27 wheat harvest to 23.8 Mt, up from 21.0 Mt last month, on higher-than-expected yields. That would be Argentina's second-largest crop on record, with harvest starting in November, adding to global wheat availability.

All eyes are on developments in the Black Sea. Russia has developed high-volume export routes outside the Azov–Black Sea basin, mainly via the Baltic Sea, which is expected to handle around 65% of the country's wheat shipments in October (LSEG). As a result, Sovecon has raised its forecast for Russia's October wheat exports to 2.8 Mt, up from 2.5 Mt a week earlier.

Ukraine is also seeking to move more grain overland, asking Poland, Romania, Slovakia and Hungary to increase transit capacity. 

Despite this movement of grain, the conflict is still ongoing, and grain markets continue to monitor developments in the Black Sea region. There was some weekly market pressure coming from renewed diplomatic efforts aimed at deescalation in Ukraine. 

Russian President Vladimir Putin met with US Special Envoy Steve Witkoff, raising expectations of a possible deescalation, which could have implications for Black Sea grain export flows. This caused some weekly market pressure.

Table 1. Global grain futures prices

Futures marketContract monthPrice per tonneChange on week
UK feed wheat Nov-2026 £193.75 −£11.25
Paris milling wheat Dec-2026 €234.00 −€9.75
Chicago wheat Dec-2026 $229.63 −$13.04
Chicago maize Dec-2026 $179.53 −$7.19

UK delivered cereal prices

To ensure our published prices remain robust and representative of the market, we are not publishing any UK delivered cereal prices as of Thursday 22 October 2026. This is because we received insufficient quotes to calculate a price fully reflective of the market. 

Rapeseed

Paris rapeseed futures in £/t, May-27

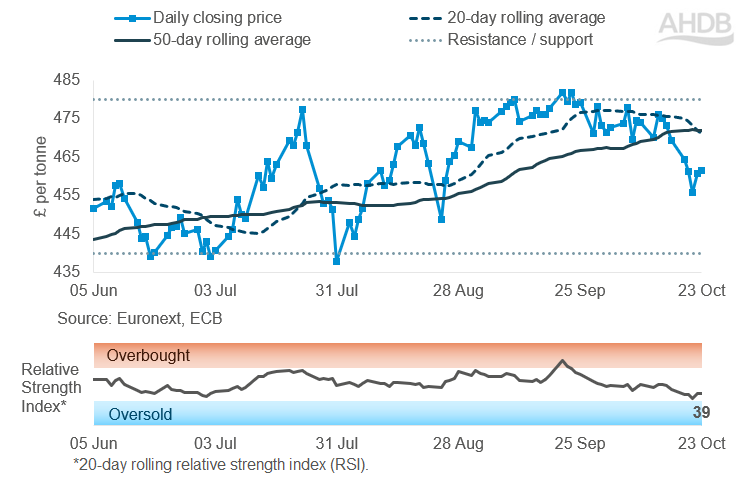
Figure 2. Paris rapeseed futures prices, Nov-26 contract, in £/tonne

The May-2027 Paris rapeseed futures contract fell 1.7% in £/t last week to approx. £461.50/t.

This is a larger fall than in euro terms due to sterling rising against the euro last week. Sterling rose from £1 = €1.1850 on 16 October to €1.1943 on 23 October, its highest exchange rate since April 2025.

The May-2027 price in £/t also moved further below both the 20-day and 50-day rolling averages. 

In Figure 1, the solid line with markers shows the price. The dashed line shows the 20-day rolling average and the solid line shows the 50-day rolling average.

However, in euro terms, the contract price remained only a little below the 50-day rolling average. It is also trading around a key psychological level at €550/t.

If the contract can hold near this level in euro terms, it could help support the price in £/t. However, this will also depend on the sterling–euro exchange rate.

Find out more about the graphs in this report and how to use them

Market drivers

Oilseed prices fell last week as the weather improved for harvesting soya beans in the US, and there was more diplomatic engagement in the Black Sea. 

However, a rise in crude oil prices in the latter part of the week helped reduce the losses from Friday to Friday. The USA also announced above-average weekly export sales of soya beans, which helped soya bean prices. 

May-2027 Chicago soya beans fell 0.6% and May-2027 Paris rapeseed futures lost 0.9%. Meanwhile, May-2027 Winnipeg canola lost 1.7%.

US representatives met both the Ukrainian and Russian heads of state last week. An announcement on Friday said negotiators from Ukraine, Russia and the USA will meet in Abu Dhabi in November.

The war continues to restrict Black Sea exports of sunflower oil and rapeseed, helping underpin prices. So, the negotiations will be watched closely. But uncertainty remains after further strikes on merchant shipping last week. 

Drier weather last week raised hopes for progress in harvesting US soya beans. The USDA issues its next report tonight.

Nearby Brent crude oil futures reached its highest price since 29 April on Friday. The contract ended the week up 6.2% at $116.72/barrel after a series of Houthi attacks on Saudi Arabia.

The ongoing conflicts and US harvest are again likely to drive markets this week. Plus, developments in South America are likely to be a factor. 

Over the weekend, Brazil re-elected President Lula for a fourth term. Reports suggest the Brazilian real could weaken against the US dollar in response to the election. 


A weaker real makes Brazilian soya beans more competitive in a market that largely trades in US dollars. This could put pressure on Chicago soya beans and, in turn, the wider oilseed market.

Meanwhile, last week the US attachés forecast the 2026/27 Brazilian soya bean crop at 184.0 Mt. This is 2.0 Mt below the USDA’s official forecast but still nearly 2% above 2025/26’s record high.

Table 2. Global oilseed and oil futures prices

Futures marketContract monthPrice per tonne*Change on week
Paris rapeseed May-2027 £551.25 −€5.00
Chicago soya beans May-2027 €471.74 −$3.03
Chicago soya bean oil May-2027 $1,490.53 −$2.43
Brent crude oil nearby $116.72 $6.86

*Brent crude oil price per barrel

UK delivered rapeseed prices

Into Erith, the delivered price for November was £462.50/t on Friday, a fall of £5.50/t from the previous week.

Into Liverpool, the price for November fell by £4.50/t Friday–Friday to £463.50/t. 

Meanwhile, the week-on-week changes for May delivered prices were slightly larger. 

The May prices into both Erith and Liverpool fell £6.00/t to £473.50/t, and the May delivered price into East Anglia declined by £6.50/t to £471.50/t.

The delivered price for harvest 2027 was £449.50/t into both Erith and Liverpool. Both prices were £6.50/t below the previous week’s survey.

Table 3. UK delivered rapeseed prices

Delivery specificationDelivery monthPrice per tonneChange on week
Erith Nov-2026 £462.50 −£5.50
Liverpool Nov-2026 £463.50 −£4.50
East Anglia Nov-2026 n/a n/a

n/a = not available

Extra information

UK supply and demand

Last week, AHDB released its first estimates of UK wheat and barley supply and demand in 2026/27. We anticipate a tighter supply and demand outlook for both wheat and barley compared to last season.

For wheat, a large drop in estimated wheat opening stocks outweighs the slight rise in production. Despite a decrease in total domestic consumption, this leads to a tighter balance sheet for wheat, with imports playing an important role in 2026/27.

For barley, the drop in availability, driven by the lowest estimated production since 2012/13, outweighs the drop in consumption. This leads to a very tight balance sheet for barley in 2026/27.

Find the estimates in full on the UK supply and demand section of our website, or read our article about the estimates. 


Futures prices

The last trading day for the Paris rapeseed futures Nov-26 contract is this Friday, 30 October.

Meanwhile, the notice period for the UK feed wheat futures Nov-26 contract begins today. This is ahead of the contract’s last trading day on Monday 23 November. 

Northern Ireland

Table 4. Delivered prices into Belfast*

Delivery specification**Delivery monthPrice (per tonne)Change on week
Feed barley – spot Spot n/a n/a
Feed barley – forward Feb-27 £221.50 –£2.00
Feed wheat – spot Spot £228.00 n/c
Feed wheat – forward Feb-27 £230.50 –£9.50

*Prices provided for indicative purposes

**Basis is imported/home-grown

n/a = not available

n/c = no comparison available


Sign up to receive the latest information from AHDB

While AHDB seeks to ensure that the information contained on this webpage is accurate at the time of publication, no warranty is given in respect of the information and data provided. You are responsible for how you use the information. To the maximum extent permitted by law, AHDB accepts no liability for loss, damage or injury howsoever caused or suffered (including that caused by negligence) directly or indirectly in relation to the information or data provided in this publication.

All intellectual property rights in the information and data on this webpage belong to or are licensed by AHDB. You are authorised to use such information for your internal business purposes only and you must not provide this information to any other third parties, including further publication of the information, or for commercial gain in any way whatsoever without the prior written permission of AHDB for each third party disclosure, publication or commercial arrangement. For more information, please see our Terms of Use and Privacy Notice or contact the Director of Corporate Affairs at info@ahdb.org.uk  © Agriculture and Horticulture Development Board. All rights reserved. 

×